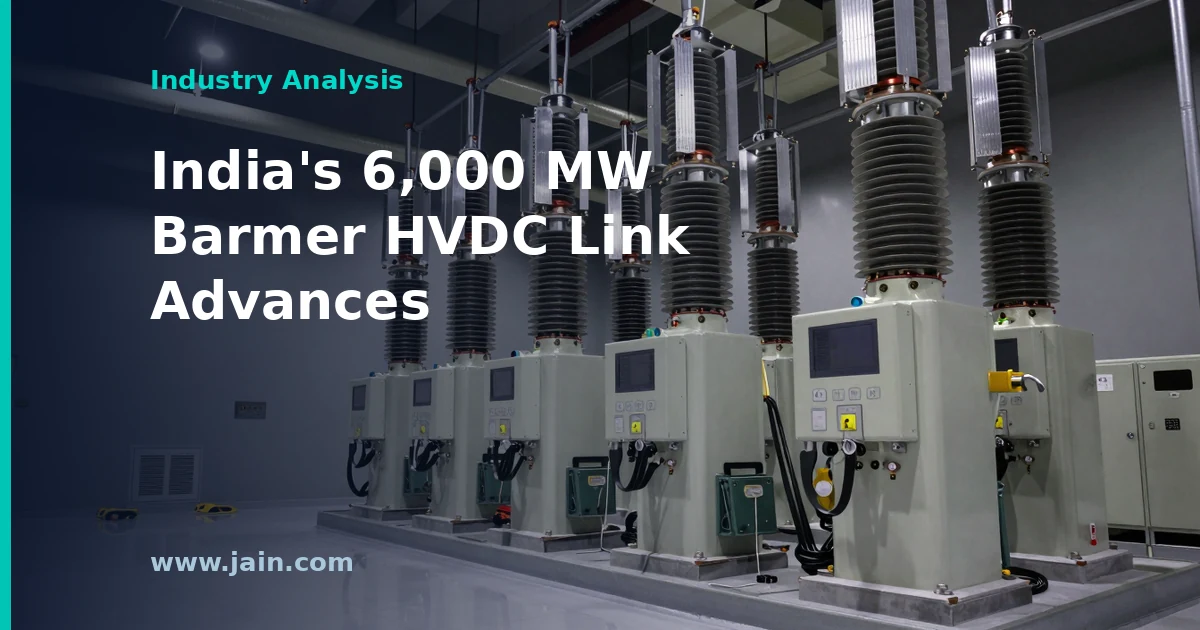
India’s state-controlled power-line company has won a project worth about 25,000 crore rupees, very roughly three billion US dollars, to build an electricity superhighway starting in Barmer, a desert district of Rajasthan crowded with solar and wind farms.
The line is designed to carry 6,000 megawatts, roughly the output of several large power stations. The Indian arm of the American company GE Vernova is reported to be the front-runner to supply the giant equipment at each end.
Why it matters: clean electricity is worthless if it cannot reach the cities, factories and data centers that need it.
Power Grid Corporation of India has secured the Barmer–South Kalamb high-voltage direct current (HVDC) transmission project, a 6,000 megawatt link valued at ₹25,000–₹26,000 crore (₹250–260 billion), Sahi Markets reported on September 7, 2026. The same report said GE Vernova T&D India emerged as the top bidder for the project’s terminal station equipment package, the converter stations that sit at either end of the line.
GE Vernova T&D India, the listed Indian subsidiary of GE Vernova, already carries an order backlog of ₹20,930 crore. Neither company has publicly confirmed the equipment award, its value or a construction schedule.
Executive Summary
The Barmer–South Kalamb award is one of the larger single transmission projects in India’s current build-out. At 6,000 megawatts, it is sized to move bulk renewable output from western Rajasthan, where land and sunshine are plentiful but local demand is modest, across long distances to consuming regions. HVDC is the technology of choice for that job because direct current loses less energy over long distances than conventional alternating current lines and lets grid operators control exactly how much power flows.
For the equipment supply chain, the significance is concentration. The terminal stations are the most technically demanding and valuable part of an HVDC system, and only a small number of manufacturers worldwide can deliver them. If GE Vernova T&D India’s reported position converts into a signed contract, it would add a substantial project to a backlog that is already more than four-fifths the size of the entire transmission scheme’s reported value.
For data center developers and other large power buyers, the story is a reminder that India’s clean-energy constraint is shifting from generation to delivery. Wind and solar capacity can be built in a few years; the transmission corridors that carry it to load centers take longer and depend on a thin supplier base.
Transmission Is Becoming the Scarce Asset
Renewable generation in India has clustered where resources are best, and Rajasthan’s Barmer region is a prime example. The problem is that the electricity is needed hundreds of kilometers away. Without enough transmission, solar and wind farms face curtailment, meaning they are ordered to cut output because the grid cannot absorb it. That makes long-distance corridors, rather than panels or turbines, the practical limit on how fast clean power reaches customers.
A 6,000 megawatt HVDC link is a direct response to that constraint. Unlike a conventional AC line, which spreads power across the network according to physics, an HVDC link behaves more like a pipeline with a valve: operators set the flow. That controllability is valuable for managing variable renewable output and for keeping regional grids stable as more intermittent supply is added.
A Narrow Supplier Base Holds Pricing Power
Converter stations, the equipment that turns alternating current into direct current and back again, are built by a small club of global manufacturers. That scarcity cuts two ways. Suppliers with local manufacturing and engineering capability, as GE Vernova T&D India has, are well placed to win work as India expands its HVDC pipeline. Buyers, meanwhile, face long lead times for transformers, valves and control systems, and limited competition on price.
A large existing backlog is both a strength and a question. The reported ₹20,930 crore order book signals demand visibility, but it also means new projects compete for the same factory slots, engineers and commissioning crews. Execution capacity, not order intake, is often what separates strong years from delayed ones in heavy electrical equipment.
What It Means for Data Center Power
India’s data center market is growing alongside rising demand for cloud and AI computing, and operators increasingly want renewable supply to meet customer sustainability targets. Most large campuses sit near major cities and connectivity hubs, not in the desert where renewable power is cheapest to generate. Corridors like Barmer–South Kalamb are what make long-distance renewable procurement, through open-access or power purchase arrangements, physically deliverable.
The project has not been tied to any specific data center or industrial customer, and it would be a stretch to read it as a data center announcement. The more measured takeaway is structural: large power buyers planning multi-year expansions in India should treat transmission timelines as a core site-selection and procurement risk, alongside land, water and fiber.
Background
India is building out large volumes of solar and wind capacity, much of it in resource-rich western states such as Rajasthan and Gujarat, far from major consumption centers. Moving that power requires new high-capacity transmission corridors, and HVDC links are increasingly used for the longest, highest-volume routes. Power Grid Corporation of India, the state-controlled central transmission utility, builds and operates much of this interstate network.
GE Vernova T&D India is the Indian-listed transmission and distribution subsidiary of GE Vernova, the energy equipment company spun off from General Electric. It manufactures and supplies grid equipment such as transformers, switchgear and HVDC systems, and it has benefited from utilities’ rising investment in grid expansion and modernization.
Four strands of coverage circulating in late August 2026 point at the same bottleneck. MarketScale reports that GE Vernova is adding HVDC (high-voltage direct current) capacity as grids work to serve data center demand. The Motley Fool notes that GE Vernova’s electrification revenue jumped 68% in a single quarter on data center deals, then asks why the stock sold off anyway. Benzinga frames a federal grid-security executive order as a reason to watch power-equipment ETFs, naming Eaton among the exposures. Yahoo Finance argues that Equinix’s AI power-grid push may reshape the investment case for the colocation operator.
None of these are primary company announcements. The material available here is headline-and-summary level aggregation, so specifics such as project sites, contract values, capital commitments and delivery dates are not established. The 68% electrification figure and the existence of the grid-security order are the two concrete claims carried by the reporting.
Executive Summary
Taken together, the four items describe a shift in where AI capacity is actually rationed. For three years the scarce input was the accelerator chip. The reporting here suggests the scarce input is now the ability to energize a site: transmission capacity, interconnection approval, transformers, switchgear and the long-lead grid hardware that sits between a substation and a server hall.
That matters commercially because the two constraints run on different clocks. Silicon supply responds to fab allocation and can loosen in quarters. Transmission responds to permitting, right-of-way acquisition, utility study queues and heavy-equipment manufacturing, which run in years. A market that can buy chips faster than it can buy amperes will reprice both — upward for anyone holding secured power, downward for anyone holding only land and capital.
The caveat is equally important. A 68% revenue jump paired with a share-price decline is a reminder that a demand narrative and a shareholder return are separate things. Growth priced in advance is not growth delivered, and a policy order is not a purchase order.
Why HVDC Suddenly Belongs in a Data Center Conversation
High-voltage direct current is unglamorous infrastructure that most data center buyers have never had to think about. Conventional grids move alternating current, which is easy to step up and down in voltage but loses meaningful energy over long distances and struggles to link grids that are not synchronized. HVDC converts power to direct current for the long haul, moves it with lower losses, and converts it back at the far end. The converter stations are expensive; the line is efficient. That trade-off only pays when you need to move a large block of power a long way.
AI campuses have made that trade-off pay more often. The cheapest and most available generation is frequently not where the fiber, the land and the tax abatements are. When local grid headroom is already committed, the choice narrows to building generation on site, waiting in an interconnection queue, or importing power from somewhere with surplus. HVDC is the third option’s enabling technology, which is why a grid-equipment vendor’s converter capacity has become a data center story rather than a utility-engineering story.
The reporting does not tell us how much capacity GE Vernova is adding, where, or on what schedule. Readers should hold that gap open. Announced capacity in heavy electrical manufacturing is a multi-year commitment, and the difference between a stated expansion and a commissioned production line is the part that determines whether 2028 projects get energized on time.
A 68% Jump and a Stock That Fell
The most quantified claim in the set is the 68% single-quarter increase in GE Vernova’s electrification revenue, attributed to data center deals. That is a large number for a business selling physical grid hardware, and it is the clearest available evidence that AI demand has genuinely reached the equipment layer rather than remaining a slide in a keynote.
The share-price reaction is the more instructive part. Equity markets price the delta against expectations, not the absolute level, so a headline growth rate can coexist with disappointment on gross margin, order intake, backlog conversion, guidance or free cash flow. Heavy electrical equipment is a business where revenue recognized today reflects orders taken years ago, and where growth funded by capacity expansion consumes cash before it produces it. A selloff on a strong revenue print is a legitimate signal that investors are asking about the quality and durability of that growth, not merely its speed.
The even-handed read is that the coverage poses the question and does not resolve it. Without segment margin, book-to-bill and guidance detail, neither the bullish framing (structural demand shift) nor the bearish framing (peak expectations) is settled by what is on the page.
Equinix and the Move From Grid Customer to Grid Participant
The Equinix item describes a colocation operator pushing further up the power stack. Colocation providers have historically bought power as an input and sold space, cooling and interconnection as a product. If power access becomes the genuinely scarce good, then procurement strategy, grid relationships and the ability to bring energized megawatts to market become the differentiator rather than a back-office function.
That is a plausible strategic logic, and the Yahoo Finance framing is appropriately conditional about it. It also cuts both ways for investors. Moving upstream raises capital intensity, lengthens payback, and imports execution risk from a domain — utility-scale power development — with a different risk profile than leasing cabinets. A REIT-like cash flow profile and a developer-like capital profile are not the same investment, and shifting between them deserves scrutiny rather than applause.
For enterprise buyers, the practical implication is simpler and more immediate. If your provider is competing on secured power, then power terms belong in the contract discussion alongside space, cross-connects and SLAs.
Policy as a Demand Signal, Not a Booked Order
The Benzinga piece reads a federal grid-security executive order as a reason to watch power-equipment ETFs, with Eaton cited among the exposures. Policy attention to grid security is a reasonable thing for the sector to track: reliability and security mandates historically pull forward spending on protection, monitoring, transformers and switchgear, and they can shift permitting posture.
The claim deserves the same scrutiny as any vendor claim. An executive order sets direction; it does not by itself appropriate money, complete a rate case, or sign a contract. Utility capital spending is approved by regulators on multi-year cycles, and equipment revenue follows funded, permitted projects. The gap between a policy signal and a delivered order is measured in quarters at best. We have not reviewed the order’s text here, so its scope, funding mechanism and enforceability remain unverified in this analysis.
Framed carefully, the four items are consistent with a real structural story — grid capacity is the gating factor on AI buildout — while none of them individually establishes its magnitude. That distinction is worth preserving as the narrative gets repeated.
Background
GE Vernova was separated from General Electric in 2024 as a standalone energy company covering power generation, wind and electrification equipment. Its electrification segment sells the physical apparatus of the grid: transformers, switchgear, protection systems and HVDC converter technology. HVDC itself is decades-old utility technology, long used for subsea links and cross-region transfers, and supplied globally by a small group of manufacturers. What is new is the demand source. Grid hardware has historically tracked slow-moving utility capital cycles rather than the compressed schedules of technology buildouts.
Equinix is one of the world’s largest colocation and interconnection operators, running data centers where enterprises, cloud providers and networks exchange traffic. Its traditional business sells space, power, cooling and connections between tenants. As AI training and inference clusters have pushed campus power requirements upward, the industry’s binding constraint has migrated from real estate and fiber toward electricity delivery, which is why colocation operators, equipment vendors and policymakers now appear in the same story.