Tag: Data Center Regulation

  • Equinix Diesel Spill in Meadowlands Puts Data Center Backup Fuel in Focus

    Equinix Diesel Spill in Meadowlands Puts Data Center Backup Fuel in Focus

    TL;DR · 30-second read

    The Short Version

    About 5,000 gallons of diesel fuel leaked from a storage tank at a large computer facility in Secaucus, New Jersey. That is roughly half of what a fuel tanker truck carries. It ran into a small creek that feeds the Hackensack River.

    The facility belongs to Equinix, which rents space to companies that run websites and online services. Cleanup crews are vacuuming fuel out of the water. State officials say the fuel did not reach the river.

    It matters because buildings like this often store large amounts of fuel for emergency generators, and nearly 100 New Jersey towns have already banned new ones.

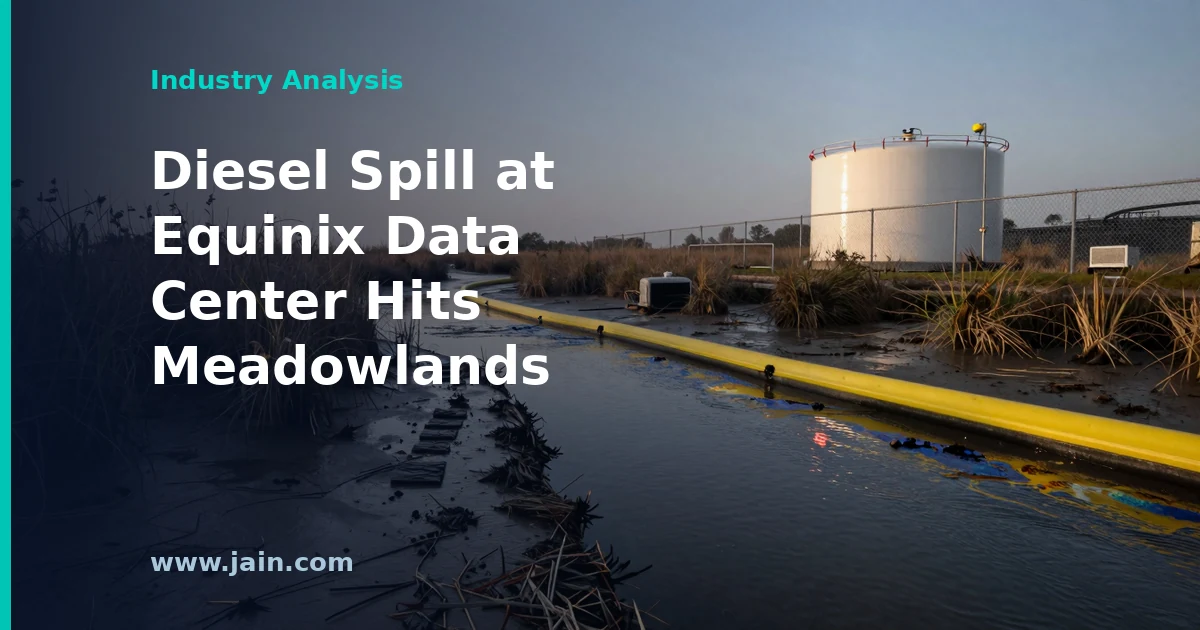
    About 5,000 gallons of diesel fuel spilled from a storage tank at the Equinix data center in Secaucus, New Jersey, and flowed into Anderson Creek, a tributary of the Hackensack River, Gothamist reported on September 14, 2026. That figure comes from the New Jersey Department of Environmental Protection (DEP). Equinix said the leak was detected on Friday evening, September 11. It has hired the environmental services contractor Clean Harbors to handle remediation.

    DEP spokesperson Larry Hajna said the creek is small and narrow where the spill occurred and that the fuel was contained before it reached the river. Crews are expected to work at the site for several days. Hackensack Riverkeeper Bill Sheehan and Secaucus Mayor Michael Gonnelli have both called for the state to pursue a natural resource damages claim against the company.

    Executive Summary

    A fuel-tank leak at one of the New York metro area’s long-established data center sites has become an environmental cleanup and a political flashpoint. Contractors placed a boom (a floating barrier) across Anderson Creek to hold the diesel in place, and vacuum trucks have been pulling a fuel-and-water mixture out for treatment and disposal offsite. Equinix said it will conduct a full investigation and is committed to resolving the situation quickly.

    The incident matters beyond Secaucus for two reasons. First, it shows a physical risk that rarely comes up in discussions of data center growth. Many facilities keep large volumes of diesel on site so that emergency generators can run during grid outages. As power availability tightens and operators lean harder on on-site backup, that fuel is a real environmental liability. Second, the spill lands in a state where close to 100 municipalities have enacted local bans on new data centers and activists are pressing the governor for a statewide moratorium.

    Local officials were measured about the facility’s history. Gonnelli said the Secaucus site had operated for 25 years without issues, and Sheehan acknowledged that data centers have been in the Meadowlands for decades without causing problems. The open questions are what caused this failure, how much fuel is recovered, and whether the state seeks penalties or restoration funding.

    The Diesel Behind the Cloud

    Data centers are usually described in terms of servers, fiber and electricity. Their resilience also depends on something far older: fuel. To stay online through a utility outage, most large facilities keep diesel generators, along with on-site storage tanks sized to run them for hours or days. Equinix has not said what the leaking tank supplied, but backup generation is the most common reason a data center stores diesel in quantity.

    That fuel is normally managed under spill-prevention rules. Typical safeguards include double-walled tanks, secondary containment berms, leak detection and regular inspections. Because roughly 5,000 gallons reached a creek, at least one of those layers did not hold. Whether the cause was a tank failure, a fueling or transfer error, damaged piping or a containment gap will determine whether this was an isolated equipment problem or a warning about practices across a fleet of aging sites.

    Grid Stress Raises the Stakes on Backup Power

    The industry’s appetite for power has grown quickly with AI workloads, and utilities in several regions have warned about constrained capacity. Generators exist to cover emergencies. But when grids run tight, operators may test them more often, keep larger fuel reserves, or run them during demand-response events, when utilities ask big users to cut grid consumption. Each of these puts more diesel on site and increases handling.

    Nothing reported so far ties this spill to increased generator use or to AI demand, and it would be unfair to draw that link without evidence. The broader point still holds for buyers and investors. The environmental risk in data center portfolios is not just carbon emissions or water use. It also includes the ordinary, local hazard of storing and moving large volumes of fuel near waterways, and that exposure grows as backup power becomes more central to operations.

    What a Damages Claim Could Mean

    Sheehan wants New Jersey to pursue a natural resource damages claim. That is a legal mechanism under which a polluter pays to restore harmed ecosystems, separate from cleanup costs or fines. He pointed to a 1994 barge spill that put 310,000 gallons of caustic soda into the Hackensack River, which he said led to dedicated funding for the restoration of Lincoln Park in Jersey City. Mayor Gonnelli said he supports that push. The DEP said it did not yet have information on potential fines or enforcement.

    Timing makes this more sensitive than a typical industrial spill. The Hackensack River was placed on the federal Superfund list, the program for the country’s most contaminated sites, in 2022, and a major cleanup is approaching. For Equinix, the direct financial exposure from remediating a contained spill is likely modest for a company of its size. The reputational and regulatory cost in a state actively debating limits on data centers could be harder to quantify.

    A Flashpoint in New Jersey’s Data Center Debate

    Opponents of data center expansion quickly cited the spill. Ben Dziobek of Climate Revolution Action Network argued that data center problems, including pollution, grid strain and higher electric bills, do not stop at municipal borders and warrant state action. Governor Mikie Sherrill’s office declined to comment and referred questions to the DEP.

    Every side’s claims deserve a fair test. This single incident, at a site local officials say ran cleanly for a quarter century, does not by itself show that data centers are environmentally unsafe. Nor does it settle the argument over electricity prices, which the spill does not bear on. At the same time, the industry’s assurances that its facilities are low-impact neighbors depend on safeguards like fuel containment actually working. Equinix’s investigation findings, and whether it shares them, will matter for more than one creek.

    Background

    Equinix is one of the world’s largest colocation data center operators. It rents secure space, power, cooling and network interconnection to enterprises, cloud providers and network carriers, and it trades on Nasdaq under the ticker EQIX. Its Secaucus facility sits in the New Jersey Meadowlands, a longtime hub for data centers serving the New York financial and media markets. Local officials say the site has operated there for about 25 years.

    The Meadowlands are a network of wetlands, creeks and tidal waterways feeding the Hackensack River, which was designated a federal Superfund site in 2022 after decades of industrial pollution. New Jersey has become a battleground over data center growth. Close to 100 municipalities have enacted local bans on new facilities, and advocacy groups are pressing for a statewide moratorium, citing pollution, grid strain and electricity costs.

    Sources

    Source: Data center spills 5K gallons of diesel into New Jersey Meadowlands (Gothamist), reporting on a diesel leak at Equinix’s Secaucus data center and the cleanup and political response.

  • Up to $1.8B in Grid Upgrades: California’s AI Data Center Deal Is About Who Pays First

    Up to $1.8B in Grid Upgrades: California’s AI Data Center Deal Is About Who Pays First

    TL;DR · 30-second read

    The Short Version

    California lawmakers have agreed on new rules for data centers, the giant warehouses of computers that run artificial intelligence and everyday online services.

    The central idea: companies building them would pay upfront for the power lines and grid upgrades their electricity demands, instead of spreading that cost across everyone’s utility bills. State grid planners estimate those upgrades in one major utility’s territory could cost up to $1.8 billion.

    The deal comes as nearly three in four Californians say they oppose data centers in their own communities, and several cities have banned or paused them.

    California lawmakers reached a compromise on Friday, Aug. 28, on legislation regulating the electricity use of data centers, the Los Angeles Times reported. The package, from Sen. Steve Padilla (D-Chula Vista) and Assemblymember Rick Chavez Zbur (D-Los Angeles), directs the California Public Utilities Commission (CPUC) to create special rates and updated rules for data centers, including how the cost of new power and infrastructure upgrades is charged.

    The final package includes the approach from Padilla’s SB 886, sponsored by The Utility Reform Network (TURN), requiring data centers to pay up front for broader grid upgrades needed to serve their demand. TURN cited a California grid operator transmission plan projecting up to $1.8 billion in upgrade costs, including transmission lines, driven by data center demand in PG&E’s service territory, where most current and proposed California data centers are concentrated.

    Executive Summary

    California has chosen a cost-allocation answer to data center growth rather than a moratorium. The deal does not cap how many facilities can be built. It changes who pays for the grid capacity they need, and when. Under the upfront-payment approach carried over from SB 886, a data center’s share of transmission and distribution upgrades becomes part of the developer’s capital budget instead of a cost recovered later from the general customer base.

    That matters because the numbers are no longer small. The California Energy Commission expects data center electricity use, now about 2% of statewide demand, to double within ten years, and the grid operator’s plan puts potential data-center-driven upgrades in PG&E territory at up to $1.8 billion. Much of the practical detail, including rate design, thresholds and timing, is left to the CPUC. Meanwhile, a provision allowing utilities to strike their own agreements with data centers before the CPUC finishes its rules creates an interim window that developers and critics will both watch closely.

    For AI infrastructure planners, the signal is mixed. The state has set a clear principle that growth pays for itself, which may reduce political risk over time. It has also added cost in a market where high power prices, scarce land and limits on gas-fired generators already hold most projects below 100 megawatts.

    The Fight Was Never About Whether, But Who Pays First

    The core dispute in Sacramento was not whether California should host data centers. It was how much they should pay for power and grid infrastructure, and whether the Legislature or the CPUC should decide. The two options on the table amount to two different financing models. When a utility builds new substations and transmission lines to serve a large new customer, the cost can either be added to the utility’s rate base and recovered over years from all customers, or charged to the customer that triggered it before the work proceeds. SB 886’s approach, which made it into the final package, leans toward the second model.

    The scale comes from the grid operator’s transmission plan, which projects up to $1.8 billion in upgrade costs from data center demand in PG&E’s territory. Moving even a meaningful portion of that onto project budgets changes a developer’s math in three ways. More capital is needed before a building is energized. Grid upgrades shift from a utility’s problem to a line item that competes with land and equipment. And a site’s value depends more heavily on how much grid headroom already exists nearby. TURN’s Matthew Freedman framed the result as keeping data center costs from “being foisted on other customers.” PG&E, which favored a less stringent approach, warned that SB 886 would “risk higher costs for customers and delay critical infrastructure,” which is a reminder that upfront payment also affects how quickly utilities can build ahead of demand.

    The groups most directly affected are developers targeting PG&E territory, which covers most of the state’s data center pipeline including the San José market, and household ratepayers, whose exposure to data-center-driven upgrades is what the deal is designed to limit. How much protection they actually get depends on rate design the CPUC has not yet written.

    A Market Already Built Small

    California enters this regime with an unusual profile. Its data centers are typically under 100 megawatts, well short of the 500-megawatt-plus AI campuses rising in other states, because of high electricity costs and state limits on gas-powered generators. The 49.5-megawatt facility under construction in Vernon is representative. For operators already constrained this way, an upfront grid charge adds to a cost stack that the Data Center Coalition’s Khara Boender says is uncompetitive: she noted that dozens of states offer data center exemptions and California does not, and called added regulation “another signal that the state is a more challenging place for data center development.”

    That argument deserves a fair hearing, and so does the counterpoint. The Coalition opposed both bills for “singling out” one type of power user. Yet the premise of cost-causation pricing is that the customer creating a large, identifiable load pays for it, and data centers are unusually concentrated loads. The strongest case on the industry’s side is not that the principle is wrong. It is that the details, such as how “broader” upgrades are apportioned among several projects on a shared line, could make early movers pay for capacity later arrivals use. That question now sits with the CPUC.

    The Interim Window and the Self-Supply Gap

    Two late amendments drew criticism from Monica Embrey of the Affordable Energy Campaign. The first allows a utility to reach its own agreement with a data center in the period before the state finalizes its rules. In practice, that creates a window in which terms are negotiated bilaterally rather than set by tariff, and projects that sign during it may lock in arrangements that differ from what the CPUC ultimately adopts. The second is the absence of clean energy requirements for data centers that generate their own power.

    Together these point to where AI campus developers are likely to focus next. If grid-supplied power carries upfront upgrade costs while self-supplied power carries no clean energy obligation, on-site or behind-the-meter supply becomes relatively more attractive, within the limits California already places on gas generators. Whether that tilt is intended, and how regulators will treat it, is one of the more consequential open questions in the package.

    Local Opposition Sets the Ceiling

    State rate rules do not settle the land-use fight playing out city by city. A Public Policy Institute of California poll in July found 73% of residents oppose data centers in their own communities. Monterey Park voters banned them outright in June, at least four other San Gabriel Valley cities have adopted moratoriums, Coachella imposed a permanent ban, and Tulare County adopted a moratorium in August. In San José, the state’s main development hub, residents have pushed for a pause while the city updates its standards.

    Water sits on a parallel track. Newsom vetoed a water-disclosure bill from Assemblymember Diane Papan last year, citing “rigid” reporting requirements, but lawmakers have since approved separate bills requiring energy and water use disclosure. For developers, the combined effect is that a California site now has to clear a cost-allocation test at the utility, a disclosure regime at the state level, and a local political test that some communities have already answered with a no.

    Background

    California has not experienced the wave of very large AI data centers seen in states such as Texas. High power prices, limited land and restrictions on gas-fired backup and primary generation have kept most facilities comparatively small, with San José and the wider PG&E service territory hosting most activity. The CPUC, whose board is appointed by the governor, regulates investor-owned utilities such as PG&E and sets the rates they charge.

    Data center growth has nonetheless become a political issue in the state. Community opposition has produced a local ban in Monterey Park, moratoriums across the San Gabriel Valley, the Coachella Valley and Tulare County, and pushback against a proposed 75-acre project in Imperial Valley. In 2025, Gov. Gavin Newsom vetoed a water-disclosure bill, citing concern about rigid requirements on critical digital infrastructure, which left energy cost allocation as the main legislative battleground in the 2026 session.

    Sources

    Source: California lawmakers reach deal in high-stakes fight over regulating data centers (Los Angeles Times), on the legislative compromise directing the CPUC to set data center electricity rates and upfront grid-upgrade charges.

  • Spain’s 80% Hourly Rule Would Make After-Dark Clean Power the Data Center Gate

    Spain’s 80% Hourly Rule Would Make After-Dark Clean Power the Data Center Gate

    TL;DR · 30-second read

    The Short Version

    Spain wants new data centers, the warehouse-sized buildings full of computers that run websites, apps and artificial intelligence, to help build the clean power they use.

    Under a draft government rule, new sites would have to get at least 80 percent of their electricity from newly built wind, solar or similar sources, checked hour by hour. That includes nights, when solar panels produce nothing.

    Sites that fall short would pay rising charges and could eventually lose their connection to the power grid. People familiar with the draft say it is not a ban, but it would make building harder.

    The Spanish government has approved a draft decree, on a fast-tracked legislative path, that would require new data centers with 1MW (one megawatt) or more of capacity to source at least 80 percent of their electricity from new renewable generation, with compliance measured hourly rather than annually. Europa Press first reported the draft on August 26, 2026, and Data Center Dynamics relayed the details. The proposal is expected to go to public consultation before it takes effect.

    The renewable supply must be additional: each new megawatt of data center capacity would be matched by equivalent renewable generation installed within the 18 months before the facility starts operating. Operators that fall short would face escalating surcharges on grid charges and network tariffs, and could ultimately lose grid access. The requirement would apply until Spain’s electricity mix reaches 90 percent renewables.

    Executive Summary

    Spain’s draft rule goes further than most corporate clean-energy commitments in three ways at once. It requires new generation rather than existing supply, it sets a high threshold of 80 percent, and it measures compliance hour by hour. It applies to new projects only, gives projects already under development a six-month grace period (three months for those awaiting a grid-access tender), and adds a requirement to meet the top tiers of a forthcoming European energy and water efficiency label for data centers.

    The stakes are large because Spain has become one of Europe’s busiest data center markets. More than 10GW (gigawatts, thousands of megawatts) of data center projects are seeking grid connections in the country. A rule that ties every new megawatt to new renewable build, matched around the clock, turns energy procurement from a sustainability line item into a precondition for getting built.

    The central consequence is less about how much clean power a project buys and more about when it arrives. Spain’s renewable strength is abundant daytime solar; an hourly test asks what supplies a data center at 3 a.m.

    Hourly Matching Moves the Problem to the Night

    Most corporate renewable claims today are settled annually. A company buys enough renewable energy over a year to equal its total consumption, and a surplus of midday solar can be counted against electricity drawn from gas or other sources at night. Spain’s draft closes that gap by measuring compliance hourly. Data centers draw close to the same power around the clock, so an 80 percent hourly test means clean supply has to be available in the evening and overnight hours as well, not just when the sun is high.

    That is why the practical constraint shifts. The reported compliance routes include onsite deployments such as rooftop solar, but rooftop solar at a facility drawing a megawatt or more covers only a fraction of its load, and only in daylight. Meeting the threshold in dark hours points operators toward wind contracts, battery storage, or power purchase agreements (PPAs, long-term contracts to buy output from a specific generator) structured around a flat, 24-hour load profile. Those products are scarcer and typically priced higher than plain solar output. The people most affected are developers in Spain’s 10GW-plus connection queue, and the winners are likely to be sellers of firmed or shaped clean power rather than sellers of cheap daytime megawatt-hours.

    The policy logic is straightforward: without additionality and time-matching, a fast-growing class of large, constant loads can absorb existing clean supply that other consumers would otherwise use, while leaving night-time demand to fossil plants. The open question is cost. An hourly 80 percent standard is materially harder and more expensive to meet than an annual one, and the draft as reported does not show how the government weighed that against the pace of investment it has been attracting.

    An 18-Month Clock Couples Two Build Schedules

    The additionality clause requires matching renewable generation to be installed within the 18 months before a data center reaches operational status. In effect, a data center’s opening date becomes dependent on a second infrastructure project: a wind farm, solar plant or storage installation that needs its own site, permits and grid connection. Delay on the generation side becomes delay on the data center side.

    That favors operators who already develop renewable assets or who can partner early with utilities and independent power producers, and it disadvantages developers who planned to sign a supply contract late in construction. It also raises the importance of the transition terms: projects already under development get six months to comply, or three months if they are waiting on a grid-access tender. For projects whose timelines were set assuming existing supply, those windows are short relative to how long new generation typically takes to build.

    The requirement is designed to expire once Spain’s electricity mix reaches 90 percent renewables. That sunset signals the rule is meant as a bridge while the grid decarbonizes, not a permanent cap, but it also means the burden falls hardest on projects built in the years before that threshold is reached.

    Enforcement Runs Through the Grid Bill

    The draft’s enforcement mechanism is notable. Rather than fines alone, shortfalls would trigger escalating surcharges on grid charges and network tariffs, with potential loss of grid access at the extreme. For a data center, grid access is the asset; putting it at risk makes compliance a matter of operational continuity, and lenders and customers signing long-term contracts will likely want to see the compliance plan before they commit.

    Layered on top is an efficiency requirement: new facilities would be expected to meet the highest levels of the European data center energy and water efficiency labeling scheme that the European Commission is slated to enforce within a year. Combined, the measures raise the bar on both how a facility is powered and how efficiently it uses that power and water.

    People familiar with the draft told Europa Press that it does not amount to a moratorium, and that is accurate on its face: nothing prohibits building. But the combination of additionality, hourly matching, short grace periods and grid-linked penalties could significantly curtail development, and it is reasonable to expect the 10GW queue to thin toward projects with credible, round-the-clock clean supply. This is one country’s draft rather than a European standard, and it is still subject to consultation, so its final shape matters as much as its headline number.

    Background

    Spain has been experiencing a data center boom, with operators drawn by its available land and strong renewable resources. More than 10GW of data center projects are currently seeking grid connections in the country, a queue that puts pressure on both grid capacity and the clean-power supply that other sectors are also counting on to decarbonize.

    The draft decree draws on two ideas that have been gaining ground in clean-energy policy: additionality, which requires that a buyer’s demand be met by newly built generation rather than existing plants, and time-matching, which checks whether clean supply is available in the same hours the electricity is consumed. Many large technology buyers have pursued these goals voluntarily; Spain’s draft would make them a regulatory condition for new data centers of 1MW and above.

    Sources

    Source: Spain drafts rules requiring data centers to source 80% of power from new renewables – report — Data Center Dynamics on Spain’s draft decree requiring new data centers of 1MW or more to source 80% of their power from new renewables on an hourly basis.

  • Michigan’s 2M-Gallon Water Cap Would Push Data Centers to Closed-Loop Cooling

    Michigan’s 2M-Gallon Water Cap Would Push Data Centers to Closed-Loop Cooling

    TL;DR · 30-second read

    The Short Version

    Michigan lawmakers have proposed a set of rules for data centers, the giant warehouses of computers that run apps, cloud services and artificial intelligence.

    The biggest of these buildings can use up to 5 million gallons of water a day, about seven Olympic swimming pools. One bill would limit the water a site can permanently use up to about three pools’ worth a day. Another would require cooling systems that reuse the same water over and over.

    Developers would also need a signed deal with the local town before they could build or connect to the power grid.

    Michigan Democrats introduced a package of bills in early July 2026 to regulate data centers’ energy use, water use, noise, labor standards and use of nondisclosure agreements, MultiState reported. The centerpiece would require operators to sign legally binding community benefit agreements with local governments before they receive site plan approvals, permits or utility interconnection. An interconnection is the approval to connect a facility to the power grid.

    The package contains competing Senate and House versions on energy and water. Senate Bill 1047 would require 20-year utility contracts and 90% clean energy procurement. House Bill 6135 would create a new large-load rate class with 15-year contracts and no clean energy mandate. On water, Senate Bill 1046 would cap consumptive use at 2 million gallons per day. The House is considering a requirement for closed-loop cooling or municipal water only.

    Executive Summary

    Michigan’s package goes beyond one-off siting fights. It would write conditions on energy, water, labor and local benefits into state law. Most permitting disputes are settled project by project in township meetings. These bills would instead set a statewide floor that every large facility would have to clear. None of the bills has passed, and the Senate and House versions differ in important ways.

    The water provisions matter most for how facilities are designed. Large data centers can use up to 5 million gallons a day. The Senate would cap consumptive use at 2 million gallons, and the House would require closed-loop cooling or municipal water. The two chambers take different routes, but both would steer developers toward cooling that evaporates less water. The community benefit agreement requirement would change the order of development. A signed local deal would come before the grid connection, not after it.

    Michigan is not alone. Six other states have considered community benefit agreement mandates this year. Twelve have weighed closed-loop cooling requirements, and twelve have weighed decommissioning rules. What stands out in Michigan is how many of these ideas arrive together in a single package.

    Two Competing Water Bills, One Direction

    Senate Bill 1046 would create a new state permit for anyone using, or expecting to use, 550,000 gallons of water or more per day. Applicants would have to hold at least three public hearings before they apply. Permit holders would face a cap of 2 million gallons per day of consumptive use. Consumptive use means water that leaves the local supply and is not returned, mostly through evaporation in cooling towers. For comparison, large data centers can use up to 5 million gallons a day. At that scale, a design that depends on evaporating large volumes of water would struggle to fit under the cap.

    The House approach is blunter. New data centers would have to use closed-loop cooling, which recirculates the same water instead of drawing and discharging fresh supply. The only alternative would be to take water solely from a municipal system. The mechanisms differ: the Senate sets a volume limit, while the House mandates a technology or a water source. The engineering result is similar. Developers planning large campuses in Michigan would be pushed toward low-evaporation cooling, whichever version prevails.

    This follows a shift the industry has already started. Operators are actively adopting less water-intensive cooling. The effects spread beyond the building itself. Cooling equipment suppliers would gain a more predictable market. Municipal water utilities could become the default supplier under the House option. Closed-loop and dry cooling generally save water but use more electricity. That puts water policy in direct contact with the energy bills moving alongside it.

    The Local Deal Would Come Before the Grid Connection

    House Bill 6137 and Senate Bill 1050 would reorder the development process. No local site plan approval, no local permit and no Public Service Commission approval of an interconnection could be issued until the local government approves a community benefit plan. For developers, the negotiation with the host community would move onto the critical path, ahead of the utility process that usually sets project timelines.

    The agreements would have to cover at least half of five listed topics, which in practice means three. The topics are local hiring, water use, cost allocation for electrical or water upgrades, community investment funding, and home efficiency improvements. A separate pair of bills, House Bill 6140 and Senate Bill 1049, would bar elected officials and operators from signing nondisclosure agreements about construction when a project receives a tax incentive. Intellectual property could still be redacted. Together, these bills would make the terms of the local negotiation largely public for subsidized projects.

    Two Chambers, Two Ways to Price Power

    The energy bills share one principle: data centers should pay for their own power, so that other ratepayers do not absorb the cost. Senate Bill 1047 would set firm terms. Contracts would run at least 20 years, customers would be billed for at least 90% of their contracted demand whether they use it or not, and applications would cost $100,000. That billing floor is aimed at the risk of a utility building for a large load that never fully arrives. The Senate bill would also require operators to procure clean energy equal to 90% of their annual usage and to join a demand response program, which pays or credits large users for cutting consumption when the grid is strained.

    House Bill 6135 would create a large-load commercial rate class with contracts of at least 15 years. Its financial terms are less strict, and it has no clean energy requirement. On the House side, House Bill 6142 would require every Public Service Commission-approved data center contract to include a decommissioning plan. The plan would need financial assurance, meaning money set aside, sufficient to cover dismantling the facility, and it would be reviewed every three years. Developers comparing states would treat the choice between these two frameworks as a real cost difference, not a technicality.

    Labor Standards, and No Moratorium

    House Bill 6141 and Senate Bill 1048 would bar the Public Service Commission from approving data center contracts unless construction and maintenance work is done under a labor agreement or collective bargaining agreement. The International Brotherhood of Electrical Workers has urged members to oppose moratorium legislation. The union argues that data centers bring well-paid construction jobs and long-term union employment. That position helps explain the package’s shape: it regulates how data centers are built, not whether they can be built.

    The package contains no moratorium and no tax incentive changes. Those questions are being handled in separate Michigan bills. They include proposals to repeal incentives, to exclude data centers from certain property tax exemptions, and to extend a brownfield-zone exemption. The package’s premise is that data centers will keep coming to Michigan and the state should set the terms, which is a middle position between welcoming them unconditionally and blocking them.

    Background

    Data centers house the servers behind cloud computing, streaming and artificial intelligence. The largest require power on the scale of a small city, and some draw millions of gallons of water a day for cooling. As construction has spread into new regions, state legislatures have moved from offering incentives to setting conditions. States considered hundreds of data center bills last year. This year, six states other than Michigan have weighed community benefit agreement mandates, twelve have weighed closed-loop cooling requirements, and twelve have considered decommissioning rules.

    Michigan’s legislature has been active on the issue throughout 2026. Separate bills address data center tax incentives: some would repeal them, one would narrow property tax exemptions, and others would extend a brownfield-zone exemption. The July package is the state’s broadest attempt yet to set operating conditions for the industry. At the federal level, a proposal from Representative Robert Bresnahan would tie federal data center tax credits to community benefit agreements.

    Sources

    Source: Michigan Data Center Legislation Targets Energy Use and Community Benefits (MultiState), an overview of Michigan’s proposed data center bills on energy, water, community benefits, noise, nondisclosure agreements and labor standards.

  • AI Data Center Moratorium Act: Ocasio-Cortez Targets the AI Build Boom

    AI Data Center Moratorium Act: Ocasio-Cortez Targets the AI Build Boom

    Rep. Alexandria Ocasio-Cortez (D-NY) has introduced the AI Data Center Moratorium Act, legislation that — as its name states — would impose a moratorium, or temporary freeze, on new AI data center construction in the United States. The bill was reported by Broadband Breakfast on June 27, 2026.

    It represents the most direct federal legislative challenge yet to the AI infrastructure boom, moving opposition from county zoning boards and state utility commissions to the floor of Congress.

    Executive Summary

    Until now, resistance to AI data center construction has been overwhelmingly local: rezoning denials, water-use disputes, and rate cases before state utility commissions. The AI Data Center Moratorium Act changes the venue. By proposing a federal pause on new builds, the bill converts a patchwork of site-by-site fights into a single national policy question about whether the AI buildout should continue at its current pace.

    The bill’s practical odds are a separate matter from its significance. Legislation introduced by a House member in the minority of a policy debate this contested rarely becomes law quickly, and nothing in the initial report indicates committee support or a Senate companion. But introduced bills do three things regardless of passage: they give opposition a national organizing document, they force industry to argue its case in federal terms, and they establish a marker that future Congresses can pick up if public sentiment shifts.

    For data center developers, hyperscalers, and the utilities planning decades of capacity around AI demand, the substance of the moratorium matters less right now than the signal: the political cost of the buildout is rising, and it has reached Washington.

    From Zoning Boards to Capitol Hill

    The AI infrastructure boom has drawn scrutiny wherever it lands — over electricity demand, water consumption for cooling, land use, and the question of who pays for the grid upgrades large facilities require. What has been missing is a federal focal point. Local opposition wins or loses one site at a time; a federal moratorium bill, even one unlikely to pass, nationalizes the argument.

    That shift matters because the industry’s siting strategy has partly relied on jurisdictional flexibility: if one county says no, a neighboring one courting tax revenue may say yes. A federal freeze would remove that option entirely, which is precisely why the industry will take the bill seriously as a signal even while discounting it as law. It also invites a counter-response — federal legislators favorable to the buildout may now push preemption or permitting-acceleration measures, making Congress a two-way battleground rather than a bystander.

    The Economics a Moratorium Would Collide With

    AI data centers sit at the center of enormous committed capital. Hyperscale cloud providers and AI developers have publicly planned multi-year construction programs, and utilities in several regions have built their load forecasts — and their generation and transmission investment plans — around expected data center demand. A construction freeze, if enacted, would ripple through all of it: land already optioned, power purchase agreements already signed, chip and electrical-equipment orders already placed.

    Supporters of a pause would frame that as the point — that commitments are being locked in faster than communities and grids can evaluate them, and that a freeze creates space to assess electricity price impacts and resource use before the buildout becomes irreversible. Opponents would argue a moratorium simply exports construction, jobs, and AI capability to other countries without pausing global demand. Both arguments deserve scrutiny against evidence: what a moratorium would actually change depends on details — scope, duration, exemptions — that the initial report does not provide.

    What Each Side Still Has to Prove

    The bill’s proponents carry a burden of evidence: demonstrating that data center growth is materially raising household electricity rates or straining water supplies in ways existing state and local review cannot manage, and that a blanket federal freeze is a proportionate remedy rather than a blunt one. Grid-cost allocation is genuinely contested territory — some utilities and regulators have moved to special tariffs that make large loads pay their own way, which weakens the case that a moratorium is the only protective tool available.

    The industry carries a symmetrical burden. Claims that data centers are net community benefits rest on tax revenue and construction employment, but permanent job counts at data centers are modest relative to their footprint, and confidential agreements around power pricing and incentives make independent verification difficult. If developers want to defeat moratorium politics, the most effective rebuttal is transparency: publishable data on rate impacts, water use, and cost allocation. Neither side’s talking points should be accepted by label alone.

    Background

    The AI boom that followed the emergence of large language models set off the fastest data center construction wave in the industry’s history, with hyperscale cloud providers and AI developers committing capital on a multi-year horizon and utilities re-planning generation and transmission around expected demand. As facilities grew from tens to hundreds of megawatts — a single large campus can draw as much power as a mid-sized city — friction with host communities grew with them, producing zoning fights, water disputes, and rate cases across the country.

    Rep. Ocasio-Cortez has long been associated with legislation linking energy, climate, and economic policy, most prominently the Green New Deal framework. The AI Data Center Moratorium Act extends that posture to AI infrastructure, and marks the first time the buildout’s opponents have consolidated their case into a proposed nationwide freeze rather than site-by-site resistance.

    Source: Ocasio-Cortez Introduces AI Data Center Moratorium Act — Broadband Breakfast, reporting the introduction of federal legislation to pause new AI data center construction, June 27, 2026.

  • Virginia Approves First Data Center Power Tax: A Precedent for AI-Era Grid Costs

    Virginia Approves First Data Center Power Tax: A Precedent for AI-Era Grid Costs

    Virginia has approved what is being described as the first-ever data center power tax, according to a June 23, 2026 report from Data Center Knowledge. The measure makes Virginia — home to the largest concentration of data centers in the world — the first U.S. state to attach a dedicated levy to data center power consumption.

    Details of the tax’s rate, structure, and effective date were not included in the initial report, but the “first-ever” framing marks a significant policy departure: rather than courting data centers exclusively with incentives, the state that hosts more of them than any other is now taxing the electricity they use.

    Executive Summary

    The significance of this measure lies less in its mechanics — which the initial reporting does not detail — than in its symbolism and its likely ripple effects. Virginia built its data center dominance in part on a generous sales-and-use tax exemption for data center equipment, a policy other states copied for two decades. A power tax moving in the opposite direction signals that the political economy of hosting data centers has shifted: the question in Richmond is no longer only how to attract capacity, but how to make that capacity pay for the grid strain it creates.

    For operators, hyperscalers, and their customers, the precedent matters more than the immediate cost. Utilities and regulators across the country have been wrestling with how to allocate the enormous transmission and generation investments driven by AI-era load growth — and whether ordinary ratepayers are subsidizing them. A dedicated tax on data center power is one answer to that question, and now the largest data center market on earth has adopted a version of it. Other states weighing similar debates will be watching closely.

    Because the available source is a headline-level report, the analysis below focuses on the policy context and the questions the measure raises, rather than on provisions that have not yet been publicly detailed.

    Why Virginia Was Always Going to Move First

    Northern Virginia — particularly Loudoun County’s “Data Center Alley” — hosts the densest cluster of data centers anywhere in the world, a position built on early internet-exchange infrastructure, proximity to federal customers, and a long-standing tax exemption on data center equipment. That concentration has made Virginia the place where the costs of the AI buildout show up first and loudest: transmission congestion, multi-year interconnection queues, land-use fights, and public concern that residential electricity bills are absorbing grid investments made largely to serve large industrial loads.

    Virginia’s own legislative auditors flagged these tensions in a December 2024 study of the industry’s fiscal and energy impacts, and the General Assembly has debated data center energy policy in every session since. Seen against that backdrop, a power tax is not a bolt from the blue — it is the next step in a multi-year negotiation between a state and an industry that has become its signature economic engine and its biggest new source of electricity demand.

    The Real Question: Who Pays for AI-Era Grid Growth?

    Electric grids recover their costs from customers through rates, and when one customer class grows explosively — as data centers have — regulators must decide whether the new transmission lines, substations, and generation get billed to that class or spread across everyone. Consumer advocates argue that spreading the cost amounts to households subsidizing some of the world’s wealthiest companies; utilities and operators counter that large, steady loads can actually lower average system costs by spreading fixed expenses over more kilowatt-hours. Both arguments have evidentiary support in different circumstances, which is precisely why the allocation fight has been so contentious.

    A tax is a blunter instrument than a rate class. Utility ratemaking assigns costs based on engineering studies of who causes them; a tax is a legislative judgment that a category of consumption should contribute more to public coffers, whatever the cost-causation math says. Whether Virginia’s measure funds grid infrastructure specifically, flows to the general fund, or offsets residential bills will determine whether it functions as genuine cost allocation or as a revenue measure wearing cost-allocation clothing. The initial reporting does not say — and that distinction is the single most important thing to watch as details emerge.

    What It Means for Operators, Tenants, and Competing States

    For data center operators, a per-unit levy on power lands directly on the largest line item in their operating budgets. Colocation providers will face the classic question of how much they can pass through to tenants under existing contracts; hyperscalers running their own facilities will absorb it as a marginal cost increase on Virginia capacity relative to other markets. The competitive effect depends entirely on magnitude: a modest levy on power in the market with the best fiber connectivity in the country changes few siting decisions, while a heavy one accelerates the diversification toward Ohio, Texas, Georgia, and the Carolinas that grid constraints were already driving.

    Competing states now face a strategic choice of their own. Some will advertise the absence of such a tax as a recruitment tool. Others — facing identical ratepayer politics as AI load arrives on their grids — may treat Virginia’s measure as proof of concept. It is worth remembering that Virginia’s data center equipment tax exemption was copied by more than thirty states. Policy that starts in the world’s data center capital has a history of traveling.

    A Precedent That Cuts Both Ways

    The industry has long argued, with some justification, that data centers are exceptional taxpayers — Loudoun County’s budget depends heavily on data center property tax revenue — and that layering new levies on top risks punishing a sector for succeeding. That argument deserves a fair hearing, and it will get one in the rate cases and legislative fights ahead. But the industry has also benefited from a bargain in which states competed to reduce its tax burden while the public bore growing grid costs, and Virginia’s move suggests that bargain is being renegotiated rather than abandoned.

    The measured takeaway: this is neither the end of Virginia’s data center industry nor a trivial development. It is the first formal acknowledgment, in statute, by the market that matters most, that data center power consumption is a distinct fiscal category. How the tax is structured — and whether it stabilizes the industry’s social license to operate or simply raises its costs — will determine whether operators come to see it as the price of durable acceptance or the start of an unwelcome trend.

    Background

    Virginia’s data center industry dates to the early internet era, when network interchange points in Northern Virginia made the region a natural home for hosting infrastructure. Over two decades, aided by a state sales-and-use tax exemption on data center equipment, Loudoun and neighboring counties grew into the world’s largest data center cluster, and data center property taxes became a pillar of local budgets. The AI boom then supercharged demand: utilities serving the region have projected sustained, historic load growth, and interconnection wait times stretched to years.

    That growth turned data centers into a live political issue in Richmond. A December 2024 state legislative audit examined the industry’s fiscal benefits and energy costs, and subsequent General Assembly sessions produced a stream of bills on data center siting, ratepayer protection, and tax treatment. The power tax reported in June 2026 is the most consequential product of that debate to date — the first time the industry’s electricity consumption itself has been made a taxable category.

    Source: Virginia Approves First-Ever Data Center Power Tax — Data Center Knowledge, June 23, 2026, reporting Virginia’s approval of the first U.S. tax targeting data center power consumption.

  • Texas Governor Calls for Regulators to Rein In Data Centers

    Texas Governor Calls for Regulators to Rein In Data Centers

    Texas Governor Greg Abbott has publicly called for regulators to clamp down on data centers, according to a June 11, 2026 report from E&E News by POLITICO headlined “Texas governor talks tough on data centers, calls for clampdown.” The remarks signal a potential policy shift in the state that has become one of the largest and fastest-growing data center markets in the United States.

    The syndicated report available to us carries only the headline, so the specific mechanisms the governor proposed — and which regulators he addressed — are not detailed in the source material.

    Executive Summary

    The significance here is less about any single proposal and more about who is speaking. Texas has spent years courting data centers with cheap power, fast permitting, abundant land, and a light-touch regulatory reputation. When the governor of that state “talks tough” and calls for a clampdown, it suggests the political calculus around hyperscale computing growth is changing even in the market most identified with welcoming it.

    The pressure has been building. Texas’ independent grid, operated by the Electric Reliability Council of Texas (ERCOT — the body that manages electricity flow for most of the state), has projected enormous demand growth driven heavily by large loads such as data centers. In 2025 the state enacted Senate Bill 6, a law giving regulators new tools to manage very large electricity users, including requirements that they be able to reduce consumption during grid emergencies. Gubernatorial rhetoric about a clampdown, if it translates into rulemaking or legislation, would extend that trajectory.

    For the industry, the message is straightforward: even in the most development-friendly major market, social license is not unconditional. Grid reliability, cost allocation, and community impact are now live political issues that developers must plan for rather than assume away.

    When the Friendliest Market Turns Cautious

    Texas — anchored by the Dallas–Fort Worth metro, one of the largest data center hubs in the world, plus fast-growing clusters in San Antonio, Austin, and West Texas — has been a primary beneficiary of the AI-driven construction boom. Developers chose Texas precisely because its political environment favored speed: deregulated retail electricity, no state income tax, and officials who actively recruited large projects. A governor from that same political tradition calling for a clampdown is therefore a meaningful signal, whatever the eventual policy details turn out to be.

    It is worth being precise about what a headline can and cannot tell us. “Talks tough” and “clampdown” are the reporter’s characterizations; the underlying remarks could range from a demand for strict new siting rules to a narrower push for large loads to pay their own way on the grid. Political rhetoric about data centers also does not always convert into binding regulation. But the direction of travel matches a broader national pattern in 2025–2026: statehouses in both parties’ hands have moved from recruiting data centers to scrutinizing them.

    The Grid Is the Battleground

    The most likely driver is electricity. ERCOT has repeatedly flagged that large flexible loads — data centers, crypto miners, industrial electrification — are the dominant source of projected demand growth, on a grid that already suffered a catastrophic failure during Winter Storm Uri in 2021. Every gigawatt of new computing load raises two politically sensitive questions: can the grid stay reliable, and who pays for the transmission and generation needed to serve it?

    Texas’ 2025 Senate Bill 6 was the first major answer, imposing interconnection requirements on very large loads and enabling their curtailment (mandatory reduction of power use) in emergencies. A gubernatorial call for further clampdown suggests officials may view those tools as insufficient — or at least politically insufficient — as residential ratepayer concerns about rising bills and water use gain traction. For an industry whose product is uptime, curtailment obligations and slower interconnection are direct commercial threats, which is why many operators are already investing in on-site generation and storage to reduce their grid dependence.

    Winners, Losers, and the Cost of Uncertainty

    If Texas tightens meaningfully, the near-term losers are speculative developers whose pipeline value depends on fast, cheap grid connections. Established operators with secured power and existing interconnection agreements arguably benefit, since barriers to entry protect incumbents. Utilities and grid operators gain leverage to demand stronger financial commitments from data center customers, reducing the risk that infrastructure is built for projects that never materialize — a growing concern given inflated interconnection queues nationwide.

    Competing markets should temper their enthusiasm, though. Rival states may market themselves as alternatives, but most face their own power constraints, and Texas’ fundamental advantages — land, energy resources, and scale — do not disappear because of tougher rules. The more realistic outcome is not an exodus but a repricing: longer timelines, more self-supplied power, and heavier upfront commitments becoming the standard cost of building in Texas. For buyers of data center capacity, that ultimately flows into pricing and delivery schedules.

    Background

    Texas rose to the top tier of global data center markets over the past decade on the strength of cheap and abundant energy, available land, fast permitting, and active state recruitment. The AI construction boom that accelerated from 2023 onward magnified that growth, with hyperscale campuses proposed across the Dallas–Fort Worth area, Central Texas, and West Texas — and with them, unprecedented projected demand on the ERCOT grid, which operates independently of the two large interconnections serving the rest of the continental U.S.

    The politics shifted as the load forecasts grew. After the deadly 2021 winter blackout exposed the grid’s fragility, Texas lawmakers grew warier of unmanaged demand growth, culminating in 2025’s Senate Bill 6, which created a regulatory framework for very large electricity users. The governor’s June 2026 call for a clampdown, as reported by E&E News, suggests that framework may have been a starting point rather than a settlement.

    Source: Texas governor talks tough on data centers, calls for clampdown — E&E News by POLITICO report, June 11, 2026, on the Texas governor’s call for regulators to rein in data center growth.

  • Utah Tightens Water and Power Rules on Kevin O’Leary’s Giant AI Data Center

    Utah Tightens Water and Power Rules on Kevin O’Leary’s Giant AI Data Center

    Utah’s governor has tightened the rules that apply to a giant AI data center project backed by investor Kevin O’Leary, according to a Business Insider report published May 30, 2026. The action places state-level conditions on one of the highest-profile celebrity-backed entries into the AI infrastructure race.

    Details of the specific requirements were not spelled out in the available source material, but the reported move fits a broader pattern: states courting AI data center investment are simultaneously attaching guardrails around the resources those campuses consume — chiefly water and electric power.

    Executive Summary

    According to Business Insider, Utah’s governor moved to tighten the rules governing Kevin O’Leary’s planned large-scale AI data center in the state. O’Leary, the investor best known from Shark Tank, has spent the past two years positioning O’Leary Ventures as a developer of very large AI computing campuses, most prominently the multibillion-dollar ‘Wonder Valley’ concept announced in Alberta, Canada, in late 2024. A Utah project extends that ambition into one of the fastest-growing — and driest — states in the American West.

    Why it matters: AI data centers are among the most resource-intensive facilities ever built at commercial scale. A single hyperscale campus can demand hundreds of megawatts of electricity — comparable to a small city — and, depending on cooling design, substantial water. Utah is an arid state where water politics are already charged, notably around the shrinking Great Salt Lake. When a governor personally intervenes to condition a marquee project, it tells the industry that resource guardrails are moving from county zoning boards up to the statehouse.

    For developers, the message is that incentives and permits increasingly come bundled with obligations. For AI tenants and investors, it means project timelines and economics now carry a regulatory variable that did not meaningfully exist three years ago.

    Guardrails Are Becoming the Price of Admission

    Through 2023 and 2024, states competed for data centers almost purely with carrots: tax abatements, fast-track permitting, cheap land. The reported Utah action reflects the next phase. Legislatures and governors in Georgia, Virginia, Texas, and elsewhere have begun asking who pays for the grid upgrades a gigawatt-class campus requires, and whether existing ratepayers end up subsidizing a private tenant’s load. Utah itself passed legislation in 2024 creating a framework for ‘large load’ customers to be served under separate terms, precisely so that massive new consumers do not shift costs onto households. Tightening rules on a flagship AI project is consistent with that trajectory: welcome the investment, but ring-fence its externalities.

    For laypeople, the key concept is that electricity and water are shared systems. A data center does not simply buy power the way a household does; at hundreds of megawatts it reshapes the utility’s entire planning horizon — what plants get built, what transmission lines get strung, and who bears the cost if the promised load never materializes.

    Water Is the West’s Hard Constraint

    Power can, eventually, be built. Water in the Great Basin largely cannot. Utah is one of the driest states in the country, and the decline of the Great Salt Lake has made every large new water commitment politically visible. Data centers vary enormously here: evaporative cooling designs can consume millions of gallons a day, while closed-loop and air-cooled designs use a small fraction of that — at the cost of higher electricity draw. Any state-imposed water condition effectively forces a design decision, pushing developers toward dry cooling and shifting the burden back onto the power system. That trade-off — water versus watts — is now a central engineering and political negotiation in every arid-state siting, and Utah’s reported action puts it on the record at the gubernatorial level.

    The Celebrity-Capital Model Meets Institutional Reality

    Kevin O’Leary’s data center ventures have been announced with characteristic showmanship — Wonder Valley in Alberta was unveiled with a headline figure of roughly $70 billion over its life. Announcements at that scale invite fair scrutiny: mega-campuses require anchor tenants, firm power agreements, water rights, transmission interconnection, and tens of billions in project finance, most of which is rarely secured at announcement time. A governor tightening the rules is, in one reading, simply the institutional system doing its job — converting a promotional vision into enforceable commitments. That is not necessarily adversarial. Projects that survive rigorous conditioning tend to be more bankable, because lenders and hyperscale tenants prefer sites where the regulatory ground has already been tested.

    Winners, Losers, and the Signal to the Market

    If the guardrails are well designed, the winners are Utah ratepayers, competing water users, and — perhaps counterintuitively — disciplined developers, who gain a clearer rulebook than rivals face in states still improvising. The risk side: conditions that are vague or shifting can chill investment, and Utah competes with Texas, Wyoming, and the Midwest for AI capital. AI tenants watching this will price in regulatory friction when choosing between states. The market signal is unmistakable either way: the era of announcing a gigawatt campus first and settling the resource questions later is closing.

    Background

    The AI boom that followed ChatGPT’s 2022 debut triggered a global race to build computing campuses of unprecedented scale, drawing in hyperscalers, private equity, sovereign funds — and celebrity investors. Kevin O’Leary entered the field through O’Leary Ventures, announcing the ‘Wonder Valley’ mega-campus in Alberta in December 2024 with a stated long-term vision of roughly $70 billion, and subsequently pursuing sites in the United States, including Utah.

    Utah, meanwhile, has courted technology infrastructure — Meta and others operate large facilities there — while wrestling with the American West’s defining constraint: water. In 2024 the state established a legal framework for serving very large new electricity loads without shifting costs to ordinary ratepayers. The reported tightening of rules on the O’Leary project sits at the intersection of those two currents: aggressive AI-infrastructure recruitment and hardening resource guardrails.

    Source: Utah’s governor just tightened the rules for Kevin O’Leary’s giant AI data center — Business Insider report, May 30, 2026, on new state-level conditions placed on the O’Leary-backed AI data center project in Utah.

  • Pennsylvania’s GRID Standards Make It an Early Mover on Data Center Accountability

    Pennsylvania’s GRID Standards Make It an Early Mover on Data Center Accountability

    Pennsylvania Governor Josh Shapiro launched new GRID standards for data center accountability on May 26, 2026, as first reported by Harrisburg-area broadcaster FOX43. Based on the initial announcement coverage, the standards are aimed at how data centers affect three things residents feel directly: electric power demand, water consumption, and the utility bills paid by ordinary ratepayers.

    Executive Summary

    The Shapiro administration’s GRID standards position Pennsylvania as one of the first states to put a governor’s name on a formal accountability framework for data centers — the large, power-hungry facilities that house cloud computing and artificial intelligence workloads. Rather than leaving oversight entirely to utility-by-utility negotiations or federal regulators, the announcement signals that the state itself intends to set expectations for how these projects account for their draw on the grid, their water use for cooling, and the costs they may shift onto other electricity customers.

    The timing matters. Pennsylvania sits inside PJM Interconnection, the largest wholesale electricity market in the United States, where capacity prices — the payments that keep power plants available — have risen sharply in recent auctions, driven in part by surging projected demand from data centers. Shapiro has already fought one public battle with PJM over those costs. The GRID standards extend that posture from the wholesale market to the facilities themselves. The initial coverage, however, is light on specifics: the announcement’s legal mechanics, thresholds, and enforcement provisions are not detailed in the source, and we flag those open questions below.

    Why Pennsylvania, and Why Now

    Pennsylvania is a natural early mover. It is one of the nation’s largest electricity producers and a net exporter of power, it has abundant natural gas, and it has been courting exactly the kind of large data center investment this framework addresses — including high-profile campus projects announced across the commonwealth over the past two years. At the same time, households in PJM territory have watched bills climb as capacity auction prices surged, and data center demand growth is one of the most frequently cited drivers. A governor who wants both the investment and re-electable utility bills has a strong incentive to formalize the rules of the road.

    Shapiro also has a track record here. His administration publicly challenged PJM over capacity auction costs, a dispute that ended with the grid operator agreeing to limit price outcomes in subsequent auctions. The GRID standards read as the demand-side complement to that supply-side fight: having pressed the market operator on prices, the state is now pressing the largest new source of demand on accountability.

    What “Accountability” Could Mean in Practice

    The announcement’s three named concerns — power, water, and ratepayer impact — map onto the three live policy debates around hyperscale computing. On power, the core issue is interconnection: when a facility requests hundreds of megawatts, who pays for the substations and transmission upgrades it triggers? On water, evaporative cooling systems can consume significant volumes, and disclosure of consumption is inconsistent across the industry. On ratepayer impact, the emerging tool nationally is the “large-load tariff” — a special rate class requiring very large customers to make long-term financial commitments so that, if a project shrinks or cancels, the stranded infrastructure costs don’t land on households.

    Which of these mechanisms Pennsylvania’s GRID standards actually employ is not specified in the initial coverage. The announcement could range from a binding framework with real teeth to a set of voluntary expectations and reporting norms. That distinction — mandatory versus aspirational — is the single most important thing to watch as details emerge, because it determines whether the standards change project economics or primarily change the political conversation.

    Guardrails as a Competitive Strategy

    The conventional worry is that regulation deters investment, and data center developers do compare states on speed and cost. But there is a credible counter-argument: clear, uniform standards can actually attract capital by replacing unpredictable, project-by-project fights — zoning battles, rate cases, water permit disputes — with a known checklist. Developers price uncertainty; a state that tells them upfront what accountability looks like may be easier to build in than one where every project becomes a referendum.

    The likely winners under a well-designed framework are utilities (clearer cost-allocation rules), communities (visibility into water and grid impacts), and large, well-capitalized operators who can meet the standards easily. The parties squeezed would be speculative projects — interconnection requests filed to reserve grid capacity without firm plans — which inflate demand forecasts and, indirectly, everyone’s bills. If the GRID standards help separate real projects from paper ones, that alone would be a meaningful service to the market.

    An Early Entry in a Coming Wave of State Rules

    Pennsylvania is not acting in a vacuum. Utility regulators in other states have been moving in the same direction through rate cases — approving special terms for very large customers so that data center growth pays its own way. What distinguishes this announcement is that it comes packaged as a governor-led, state-level framework rather than a utility-specific tariff proceeding, which gives it broader scope and higher political visibility.

    That makes it a template other governors will study. If Pennsylvania can pair accountability standards with continued project announcements, it strengthens the case that guardrails and growth are compatible. If investment visibly slows, critics will attribute it to the standards — fairly or not. Either way, the experiment will generate the evidence the rest of the country currently lacks, and the industry should engage with it on that basis rather than treating any state framework as inherently hostile.

    Background

    Pennsylvania is one of the largest electricity-producing states in the country and a longtime net exporter of power, with deep natural gas resources and a legacy nuclear fleet. That energy abundance, together with available land and fiber routes between East Coast metros, has made it a serious contender for hyperscale data center campuses as the artificial intelligence buildout accelerated through 2024–2026, including multibillion-dollar projects announced across the commonwealth.

    The same period strained the region’s electricity economics. Capacity prices in PJM Interconnection — the wholesale market serving Pennsylvania and much of the eastern U.S. — rose sharply in successive auctions as demand forecasts swelled, and Governor Shapiro emerged as one of the most vocal state-level critics of those outcomes, pressing PJM to limit costs borne by consumers. The GRID standards announced May 26, 2026 are the next step in that arc: moving from contesting wholesale market prices to setting state-level expectations for the facilities driving demand.

    Source: Shapiro launches new GRID standards for data center accountability — FOX43 (Harrisburg, PA) report on the governor’s May 26, 2026 announcement.