An entity calling itself the Transatlantic Investment Group announced on April 27, 2026 a €50 billion AI data center and innovation campus in Croatia. The announcement describes the project as the largest investment in Croatian history and among the largest private U.S. investments in Europe. Beyond that headline framing, the release provides few operational details — no named site, power figure, timeline, or anchor tenant.
Executive Summary
The announcement positions Croatia — an EU, eurozone, and Schengen member on the Adriatic — as the destination for one of the largest AI infrastructure commitments ever declared in Europe. A €50 billion figure, if realized, would place the project in the same conversation as the multi-hundred-billion-euro wave of AI campus announcements that has swept the U.S. and, increasingly, Europe and the Gulf since 2024.
Why it matters: hyperscale AI buildout is going global. Power, land, and permitting constraints in Europe’s established data center markets — Frankfurt, London, Amsterdam, Paris, Dublin — have pushed developers toward secondary markets, and a commitment of this size in Croatia would be the strongest signal yet that the frontier has moved to Southeast Europe. But the announcement, as published, is a statement of intent. The distance between a declared figure and energized capacity is measured in grid connections, financing closes, and construction phases — none of which are detailed here. Readers should treat this as a significant claim awaiting substantiation, not a shovel-ready project.
Why Croatia? The Logic of AI’s Geographic Spillover
Europe’s traditional data center hubs are effectively full. Utilities in Dublin and Amsterdam have restricted new grid connections for large facilities, and Frankfurt and London face similar power and land pressure. That has redirected capital toward markets that can offer three things at once: available power, developable land, and EU regulatory standing. Croatia checks the third box cleanly — it is inside the EU single market, the eurozone, and Schengen — which matters for data sovereignty rules that push European enterprises and governments to keep AI workloads on EU soil.
The strategic framing as a “private U.S. investment in Europe” also fits a broader pattern: American capital funding AI capacity abroad, both to serve regional demand and to diversify away from congested U.S. power markets. For Croatia, a country whose economy leans heavily on tourism, an anchor investment in digital infrastructure would be transformative — which is precisely why the announcement’s superlatives deserve careful measurement against what has actually been committed.
What €50 Billion Buys — and What an Announcement Doesn’t
At current costs, hyperscale AI capacity runs very roughly in the tens of millions of euros per megawatt once you include the chips inside. A €50 billion program therefore implies gigawatt-class ambitions — a campus that would rank among the largest in Europe and consume electricity on the scale of a sizable city. Nothing in the announcement explains where that power comes from, and in AI infrastructure, power is the project. Grid interconnection queues, not capital, are the binding constraint almost everywhere.
Industry observers have also learned to discount announcement figures. Across the sector, headline commitments are typically phased over a decade, contingent on demand, and structured so that early phases are a small fraction of the total. That is not a criticism of this project specifically — it is how large campuses are legitimately built — but it means the meaningful milestones to watch are land acquisition, a signed grid agreement, a financing close, and a named hyperscale or AI-lab tenant. None appear in the source material.
Winners, Losers, and the Regional Ripple
If even a first phase proceeds, the beneficiaries are identifiable: Croatia’s grid operator and power producers (who would need to expand generation and transmission), regional construction and electrical trades, European chip-adjacent suppliers of cooling and power equipment, and connectivity providers building fiber routes to link the Adriatic to Frankfurt, Milan, and Vienna. An “innovation campus” component, if real, could seed a local AI workforce — though such components are also the easiest part of an announcement to promise and the last to be funded.
The competitive question is who this capacity would serve. Europe’s AI compute demand is growing, and the EU has actively courted large-scale AI infrastructure through initiatives like its AI gigafactory push. But Croatia would be competing with Spain, the Nordics, and Southern European markets that offer abundant renewables and established subsea connectivity. A project of this scale succeeds or fails on tenant demand, and the announcement names none.
Background
Croatia joined the European Union in 2013 and adopted both the euro and Schengen membership in 2023, completing its integration into the EU single market. Its economy has historically leaned on tourism and shipping, with a small but growing technology sector; it has not previously hosted hyperscale data center capacity, which in Europe has concentrated in the so-called FLAP-D markets — Frankfurt, London, Amsterdam, Paris, and Dublin.
That concentration is now breaking up. Power and land constraints in the established hubs, EU data sovereignty rules encouraging in-region AI capacity, and Brussels-backed initiatives to attract large-scale AI computing have pushed developers toward Southern and Eastern Europe. The Croatian announcement, if substantiated, would be the largest expression of that shift to date.
Anthropic, the AI lab behind the Claude family of models, is pursuing a push into European AI data centers and is recruiting for a key dealmaking role to drive it, according to a CNBC report published April 26, 2026. The report signals that Anthropic intends to secure compute capacity in Europe directly, rather than relying solely on its cloud partners — though no sites, capacity figures, or financial commitments have been disclosed.
Executive Summary
According to CNBC, Anthropic is working to expand its AI data center footprint in Europe and is hiring for a senior dealmaker position to lead infrastructure negotiations. A “dealmaker” hire in this context typically means someone who structures large, complex transactions — capacity leases, joint ventures, land and power agreements — rather than a conventional corporate development role.
The move matters because it marks a broader industry shift: frontier AI labs, which historically consumed compute through hyperscale cloud providers, are increasingly acting like infrastructure buyers in their own right. If Anthropic contracts European capacity directly, it becomes a new class of anchor tenant — or even developer — in a market already straining under power and land constraints. For data center operators, utilities, and governments courting AI investment, that changes who sits across the negotiating table.
From Tenant to Buyer: Frontier Labs Are Changing Seats at the Table
Until recently, the division of labor in AI infrastructure was clean: labs trained models, cloud providers built and operated the data centers. Anthropic has historically run its workloads on partner infrastructure, backed by deep compute relationships with Amazon and Google. Recruiting a dedicated dealmaker for a European push suggests the company wants direct agency over where its capacity sits and on what terms — the same trajectory other frontier labs have followed as training and inference demand outgrew what standard cloud contracts comfortably deliver.
The economics explain the shift. AI compute is now the dominant cost line for a frontier lab, and multi-year capacity commitments are effectively infrastructure finance decisions. Negotiating directly with data center developers, power providers, and governments can secure capacity earlier and potentially on better terms than consuming it through an intermediary — but it also requires skills labs did not traditionally employ: site selection, power procurement, and structured real-estate-style dealmaking. A dealmaker hire is the organizational tell that this capability is being built in-house.
Why Europe: Sovereignty Demand Meets a Supply-Constrained Market
Europe is a logical but difficult target. On the demand side, European enterprises and public-sector buyers increasingly want AI workloads processed in-region — a mix of data-protection law, the EU AI Act’s compliance regime, and a broader political push for “sovereign AI” capability. A lab that can offer European customers inference served from European soil holds a genuine commercial and regulatory advantage over one that cannot.
On the supply side, however, Europe’s prime data center markets — Frankfurt, London, Amsterdam, Paris, Dublin — are among the most power-constrained in the world, with grid-connection queues stretching years and some jurisdictions having imposed moratoria on new builds. That scarcity is precisely why a dealmaker matters: available large-scale capacity in Europe is won through early, creative transactions — secondary markets, powered-land deals, partnerships with utilities — not by placing an order. Anthropic entering that hunt adds a well-capitalized bidder to an already competitive field.
Ripple Effects: Operators, Hyperscalers, and Governments
For European data center operators and developers, a frontier lab shopping directly is attractive: AI labs sign large, long-duration commitments that can anchor entire campuses and underwrite new construction. Utilities and grid operators face the harder version of the same news — more gigawatt-scale demand arriving in systems already juggling electrification and renewable-integration timelines.
For the hyperscalers, the picture is nuanced rather than adversarial. Anthropic’s cloud partnerships remain central to its compute story, and a European buildout could well be executed with or through those partners. But every direct deal a lab signs shifts some negotiating leverage and some margin away from the cloud intermediary. Governments, meanwhile, gain a new courtship target: expect member states competing for AI investment to treat frontier labs, not just hyperscalers, as strategic accounts.
Background
Anthropic was founded in 2021 by former OpenAI researchers and has grown into one of the leading frontier AI labs, best known for its Claude models. Its compute has historically come through deep partnerships with Amazon — which has committed roughly $8 billion in investment — and Google, both of which also serve as cloud infrastructure providers for its training and inference workloads.
The European data center market it is now reportedly entering is large but supply-constrained: the established FLAP-D hubs (Frankfurt, London, Amsterdam, Paris, Dublin) face power scarcity and permitting friction, pushing new AI capacity toward secondary markets such as the Nordics, Iberia, and Southern Europe. European policymakers, for their part, have been actively courting AI infrastructure investment as part of a broader push for regional AI capability.
A 9-gigawatt AI data center campus backed by investor Kevin O’Leary has been approved in Utah, according to an April 26, 2026 report from Tom’s Hardware. The project is described as generating and consuming more than twice the amount of power the entire state of Utah currently uses — placing it among the largest data center developments ever announced anywhere in the world.
Executive Summary
The headline fact is the scale: 9 gigawatts is not a data center in any conventional sense — it is a power project with computing attached. For perspective, 9GW is roughly the output of nine large nuclear reactors, and the report frames it as more than double Utah’s entire statewide electricity draw. Notably, the report says the campus will generate as well as consume that power, which signals a behind-the-meter model: building dedicated generation on site rather than asking the regional grid to supply it.
The second fact is the word “approved.” Some jurisdictional body has said yes to something — but at headline level, the report does not specify which approval this is: land-use zoning, an air-quality permit, a generation license, or a state economic-development agreement. In mega-project development, each of those is a different gate, and clearing the first one is a long way from moving dirt. What is substantiated here is an approval milestone for an extraordinarily ambitious plan; what is not yet substantiated is financing, customers, a construction timeline, or the generation technology behind the 9GW figure.
A Power Plant First, a Data Center Second
The most telling detail in the report is that the campus will “generate and consume” its power. AI campuses at gigawatt scale have collided with a hard constraint across the United States: utility interconnection queues — the waiting lines to connect large new loads to the grid — now stretch years in many regions. Developers who cannot wait are going behind the meter, building their own gas turbines, and in some proposals nuclear or geothermal capacity, dedicated to the site. A 9GW self-generation plan sidesteps the queue but inherits a different set of problems: gas turbine order books are backed up years, fuel supply must be contracted at enormous volume, and on-site generation still typically requires air-quality permits and some grid tie for backup and startup power.
For lay readers, the practical meaning is this: the binding constraint on AI infrastructure has shifted from chips and buildings to electricity. Projects are now sized and sited around where power can be created, not where fiber or customers happen to be. Utah — with land, gas access, and a development-friendly posture — fits that new map.
What “Approved” Does and Does Not Mean
Approval is a genuine milestone; it is also the cheapest one. The industry has spent the past two years in an announcement race, with proposed multi-gigawatt campuses in the U.S., Canada, and the Gulf states collectively promising far more capacity than the supply chain — turbines, transformers, switchgear, chips, and skilled labor — can deliver on the advertised timelines. Analysts increasingly distinguish between announced gigawatts and energized gigawatts, and the gap between the two is wide. Kevin O’Leary himself previously announced a separate multi-gigawatt AI data center park in Alberta, Canada, which illustrates the pattern: high-profile backers can secure land and early approvals quickly, while the capital-intensive middle of the project — measured in tens of billions of dollars for a campus this size — takes years and committed tenants to close.
None of that makes the Utah project unserious. It makes it unproven, which is the honest status of nearly every gigawatt-class announcement at the approval stage. The credible test will be what follows: named anchor tenants, equipment orders, and financing commitments, not renderings.
Winners, Losers, and the Utah Question
If the campus advances, the near-term winners are clear: turbine and electrical-equipment manufacturers with the scarcest order slots, construction and trades labor in Utah, and the state’s tax base. Hyperscalers and AI labs hungry for capacity gain another potential supply option in a market where powered land is the scarcest commodity. The open question is who bears the risks. Behind-the-meter gas generation at this scale raises air-quality and emissions questions; data centers in the arid West raise water and cooling questions; and residents near any 9GW generation complex will have views on all of it. A project sized at more than twice the state’s current consumption will, fairly or not, become a referendum on how Utah wants to participate in the AI buildout — and community sentiment has already slowed or stopped large data center proposals in other states. Developers who engage those concerns early, with specific commitments on emissions, water, and grid impact, have fared better than those who lead with the gigawatt number.
Background
The AI boom has turned electricity into the data center industry’s scarcest input. Training and running large AI models requires dense clusters of power-hungry chips, and since 2023 developers have raced to secure “powered land” — sites where gigawatt-scale electricity can be delivered or built. With utility interconnection queues stretching years, a new class of power-first campuses has emerged that builds its own generation on site, and announced capacity across North America and the Gulf now far outstrips what has actually been energized.
Kevin O’Leary, the investor and Shark Tank personality behind O’Leary Ventures, entered this race with a previously announced multi-gigawatt AI data center park in Alberta, Canada. The Utah campus extends that playbook to the U.S. at even larger scale: at 9GW, the approved plan would exceed the entire current power draw of the state that will host it — a first even by the standards of this buildout.
A project profile published April 25, 2026 by Northwise Project details a 310 megawatt (MW) data center in Lappeenranta, Finland attributed to Nebius Group, the Amsterdam-headquartered AI infrastructure company that trades on Nasdaq under the ticker NBIS. The report frames the facility as an “AI factory” — a data center purpose-built for training and running artificial-intelligence models rather than for general-purpose computing.
At 310 MW, the Lappeenranta site would sit firmly in the top tier of European data center projects by power capacity, and would extend Nebius’s existing Finnish footprint, anchored by its long-running campus in Mäntsälä.
Executive Summary
The headline fact is the number: 310 MW of power capacity dedicated to AI computing in a single Finnish location. Power capacity — the electricity a facility can draw and convert into computation — has become the standard yardstick for AI infrastructure because modern graphics processing units (GPUs) are constrained less by floor space than by the megawatts available to feed and cool them. A conventional enterprise data center might draw a few megawatts; 310 MW is the scale at which a facility can host tens of thousands of accelerators and compete for the largest AI training workloads.
The location is just as telling as the size. Finland offers a cool climate that slashes cooling costs, a grid that is among Europe’s most carbon-free, political stability inside the EU, and — in Nebius’s case — years of accumulated operating experience in the country. Lappeenranta, a university city in southeastern Finland, adds a local energy-engineering talent base.
What the profile does not settle is equally important: it is a single third-party report, and details on timeline, phasing, investment, power contracts, and customers are not substantiated in the source material. The scale claim is specific, but readers should treat the project’s parameters as reported rather than independently confirmed.
Why Finland Keeps Winning AI Capacity
Finland has quietly become one of Europe’s most competitive destinations for compute-intensive infrastructure, and the reasons are structural rather than promotional. Cooling is one of the largest operating costs in a data center, and Finland’s climate allows “free cooling” — using outside air or nearby water — for much of the year. The Finnish grid is also unusually clean, drawing heavily on nuclear, hydro, and wind, which matters both for operating economics and for AI customers facing sustainability reporting obligations in the EU.
Nebius knows this terrain better than most entrants. Its Mäntsälä campus, inherited from the company’s pre-2024 corporate history, is well known in the industry for piping waste heat from servers into the local district heating network — turning a cost center into community energy. A second, far larger Finnish site would suggest the company is doubling down on a playbook it has already proven, rather than experimenting in an unfamiliar market.
What 310 MW Actually Buys
For readers outside the industry: data centers are sized by power, not square footage, because electricity is the true scarce input. A 310 MW facility operates on a different plane from traditional colocation sites. Individual AI server racks now draw 100 kilowatts or more — ten times the density of conventional racks — so hundreds of megawatts translate into the tens of thousands of GPUs needed to train frontier-scale models.
The “AI factory” framing is more than marketing shorthand. Purpose-built AI facilities differ from general-purpose data centers in their electrical distribution, liquid-cooling infrastructure, and network fabric, which must move enormous volumes of data between GPUs at very low latency. Retrofitting a legacy facility to these specifications is often harder than building new — which is why the current AI cycle is producing greenfield gigascale campuses rather than expansions of existing colocation stock.
Nebius and the Neocloud Race
Nebius belongs to a category investors have taken to calling “neoclouds”: companies that rent GPU capacity for AI workloads, competing with the hyperscale clouds on price, availability, and specialization. The strategic logic of a 310 MW owned site is vertical integration — controlling land, power, and buildings rather than leasing from wholesale data center providers should yield structurally lower cost per GPU-hour, which is the metric on which this market ultimately competes.
The risk side of that logic is capital intensity. Facilities at this scale require investment in the billions of dollars before revenue arrives, and the GPU rental market is young, with demand concentrated among a relatively small set of AI labs and enterprises. A purpose-built AI factory is a leveraged bet that today’s extraordinary demand for training and inference capacity persists through the multi-year window it takes to permit, build, and fill such a site. That bet may well pay off — but it is a bet, and the source material offers no visibility into how this one is financed or contracted.
Europe’s Sovereignty Subtext
A gigascale AI facility on EU soil lands in the middle of Europe’s “sovereign AI” debate — the push to ensure European companies and governments can access frontier compute under European jurisdiction rather than depending entirely on U.S.-based capacity. An Amsterdam-headquartered operator building hundreds of megawatts in Finland fits that narrative neatly, and European AI startups and public-sector buyers are an obvious customer constituency.
Whether the project actually serves that market, or is absorbed by one or two large anchor tenants, is not something the source addresses. The distinction matters: a facility serving broad European demand changes the region’s compute landscape; a facility pre-committed to a single large customer changes one company’s supply chain. Both are legitimate businesses, but they have different implications for European AI buyers watching capacity announcements with interest.
Background
Nebius Group took its current form in 2024, when Yandex N.V. — the Dutch holding company of the Russian internet group — sold its Russia-based businesses and rebuilt itself around international assets, including a data center in Mäntsälä, Finland. Rebranded as Nebius and relisted on Nasdaq under the ticker NBIS in October 2024, the company positioned itself as a European-rooted provider of AI cloud infrastructure, backed by partnerships in the Nvidia ecosystem and an aggressive data center expansion program across Europe and beyond.
The broader backdrop is a global scramble for AI compute. Training and serving large AI models requires unprecedented concentrations of GPUs and electricity, and power availability has replaced land or fiber as the industry’s gating resource. The Nordics — with cool climates, clean grids, and supportive municipalities — have become one of the main theaters for this build-out, and Finland in particular has converted those advantages into a steady pipeline of hyperscale and AI-specialized projects.
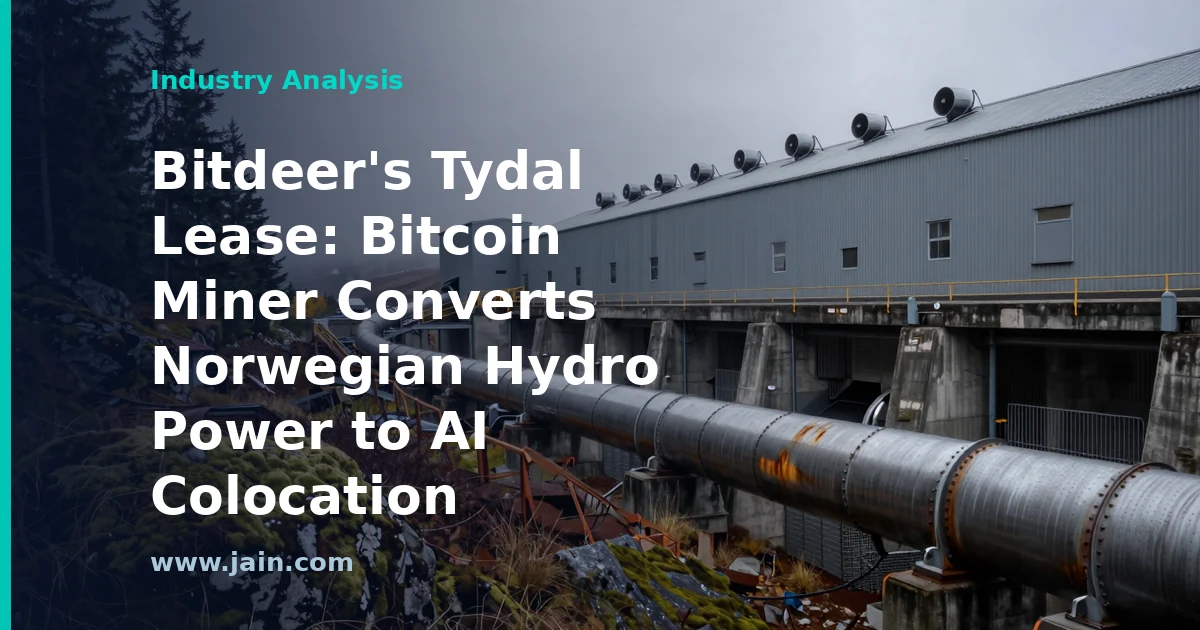
Bitdeer Technologies Group, the Nasdaq-listed bitcoin mining and data center company, has signed a colocation lease covering an AI data center at its site in Tydal, Norway, according to an April 24, 2026 report from Blockspace Media. Colocation means Bitdeer will act as landlord and facility operator, leasing powered, cooled data center space to a tenant that installs its own computing equipment.
The deal marks a concrete step in Bitdeer’s effort to convert part of its hydro-powered Norwegian footprint — originally built to mine bitcoin — into longer-duration AI infrastructure revenue.
Executive Summary
The announcement is notable less for its size — key commercial terms were not disclosed in the source report — than for what it represents: a signed lease, not a strategy slide. Over the past two years, most large bitcoin miners have announced intentions to pivot toward AI and high-performance computing (HPC), but the market has learned to distinguish between aspirational capacity announcements and executed contracts with tenants. A colocation lease at Tydal puts Bitdeer in the smaller group with a binding commercial agreement.
Tydal sits in central Norway, a region with abundant hydroelectric generation, a cool climate that reduces cooling costs, and historically low industrial power prices. Those attributes made it attractive for bitcoin mining; they are arguably more valuable for AI workloads, where customers pay a substantial premium per megawatt over what mining economics can support. For Bitdeer, swapping volatile, bitcoin-price-linked mining revenue for contracted lease income changes the character of the business — closer to a data center REIT than a commodity producer.
For the broader industry, the deal is another data point that the miner-to-AI conversion trend is producing real transactions, particularly at sites with cheap, clean, already-secured power.
Why Miners Are Becoming Landlords
The economic logic of the miner-to-AI pivot is straightforward: the scarcest input in AI infrastructure today is not chips but energized data center capacity — sites with grid connections, substations, and permits already in hand. Bitcoin miners spent a decade accumulating exactly that. Securing a new large-scale grid connection in most Western markets can take years; a miner with an operating site can, in principle, offer a tenant powered space far sooner.
The revenue math strengthens the case. Bitcoin mining revenue per megawatt is capped by network economics and falls with every halving of mining rewards, while AI tenants — cloud providers, GPU-cloud startups, and enterprises — have shown willingness to sign multi-year leases at rates mining cannot match. Converting a site from mining to AI colocation typically requires significant re-engineering, since AI servers demand far higher rack densities, more sophisticated cooling, and stricter reliability standards than mining rigs. But where the power and land are already in place, the conversion cost is generally lower than greenfield construction.
Norway’s Quiet Advantage in the AI Buildout
Norway rarely features in headlines dominated by Virginia, Texas, and the Gulf states, but it holds a strong hand: electricity that is overwhelmingly hydroelectric, among the lowest industrial power prices in Europe, a cold climate that allows free-air cooling for much of the year, and political stability. For AI customers facing sustainability reporting requirements — particularly European enterprises subject to EU disclosure rules — hydro-powered capacity carries genuine commercial value, not just marketing value.
The counterweights are real, too. Norway is far from the major European population centers, which adds network latency — a concern for user-facing AI inference, though far less so for model training, which tolerates distance well. Norwegian grid operators have also grown more selective about allocating power to data centers, and transmission constraints between Norway’s regions mean cheap power is not uniformly available. A site like Tydal, with an existing connection, is therefore more valuable than a map of Norwegian hydro resources might suggest.
Colocation Versus the GPU-Cloud Gamble
Bitdeer’s choice of a colocation lease — rather than buying GPUs and selling computing capacity itself — is a meaningful strategic signal. Miners pursuing the pivot face a fork: the asset-light path (lease space to a tenant who owns the chips) or the asset-heavy path (borrow to buy GPUs and operate a cloud). The colocation route earns lower headline revenue per megawatt but avoids the two biggest risks of the GPU-cloud model: rapid hardware depreciation as new chip generations arrive, and customer concentration in a market where a handful of AI labs dominate demand.
A lease also gives investors something mining never could: contracted, forecastable cash flow. How much credit Bitdeer earns for that depends on terms the report does not disclose — tenant identity and creditworthiness, lease duration, and who funds the conversion capital expenditure. Those details, more than the existence of the lease itself, will determine how the deal is ultimately judged.
What It Means for the Competitive Landscape
Each executed miner-to-AI deal tightens the market for the remaining players. Sites with cheap, clean power and existing interconnection are a finite inventory, and tenants signing leases today are effectively optioning that inventory ahead of rivals. For traditional data center operators, miners converting capacity represent new competition from an unexpected direction — though one that must still prove it can meet enterprise reliability expectations, which are far stricter than mining’s tolerance for downtime.
For other miners, the signal is double-edged. Successful conversions validate the strategy, but they also raise the bar: as more signed leases accumulate across the sector, companies still marketing unconverted ‘AI-ready’ capacity without tenants will face sharper investor questions about why their sites have not attracted commitments.
Background
Bitdeer Technologies Group went public on Nasdaq in 2023 and grew into one of the larger publicly traded bitcoin mining operators, building power-intensive computing facilities in markets with inexpensive electricity — including hydro-rich Norway. Bitcoin mining ties revenue directly to the cryptocurrency’s price and to network ‘halvings’ that cut mining rewards roughly every four years, pushing miners to seek steadier income from their energy assets.
Since the generative-AI boom began straining global data center supply, miners collectively controlling gigawatts of secured grid capacity have emerged as unexpected suppliers of AI infrastructure. Several have signed high-profile AI hosting and colocation agreements, and investors now reward executed contracts far more than announced ambitions — the context in which Bitdeer’s Tydal lease lands.
ABB has introduced a 34.5kV version of its HiPerGuard medium-voltage uninterruptible power supply, announced on 22 April 2026. The company positions the product as connecting directly to a medium-voltage grid feed, eliminating conversion steps between the utility connection and the data center’s power train, and says the result is lower power costs for AI data centers.
At 34.5kV, the unit sits at the top of the medium-voltage distribution class commonly used by North American utilities. The announcement is a product-capability disclosure rather than a customer deployment: the material published alongside the headline does not name sites, buyers, delivery dates or measured efficiency gains.
Executive Summary
An uninterruptible power supply is the equipment that keeps a data center’s servers running through a grid disturbance, bridging the seconds or minutes until generators take over. Conventionally, that equipment lives at low voltage — typically a few hundred volts — which means utility power arriving at medium voltage must first be stepped down through transformers, then protected, then distributed. Every one of those stages costs a percentage of the power passing through it, and each percentage becomes heat that must itself be cooled.
ABB’s claim with the 34.5kV HiPerGuard is that the UPS can sit further upstream, taking the medium-voltage feed directly and removing conversion stages from the chain. The commercial argument is straightforward: fewer stages mean fewer losses, less transformer and switchgear capacity to buy, and less floor space consumed by electrical rooms that could otherwise hold revenue-generating IT equipment.
The timing matters more than the voltage number. AI training and inference racks have moved from tens of kilowatts to the hundreds, with megawatt-scale racks on vendor roadmaps. At those densities the electrical distribution system, not the building shell, becomes the constraint. Medium-voltage UPS is one of several architectural responses to that constraint — and this announcement is a claim about a direction of travel that the released material does not yet quantify.
Voltage Is the New Density Lever
Power density in data centers has historically been solved by moving air and water more cleverly. That era is ending. When a single rack draws hundreds of kilowatts, the limiting factor shifts to how much current the distribution system can carry without unmanageable conductor sizes, losses and fault energy. Physics is unhelpful here: for a given amount of power, halving current requires doubling voltage, and copper cost and resistive loss scale with current, not with power.
Raising the voltage at which protected power is handled is therefore one of the few structural levers available. Doing it at the UPS means the medium-voltage feed can travel deeper into the facility before being stepped down close to the load, shortening the low-voltage runs that dominate conductor spend. It also compresses the equipment chain: each transformation stage carries its own footprint, maintenance regime, failure modes and efficiency penalty. Removing stages removes all four at once.
The counterpoint worth stating plainly is that this is a re-architecture, not a component swap. Medium-voltage equipment brings different clearance requirements, different arc-flash considerations, different qualification standards for the technicians who work on it, and a smaller pool of contractors able to commission it. Operators who adopt it are trading one set of engineering problems for another, and the trade only pays at scale.
Where the Savings Actually Come From
The headline frames the benefit as lower power costs. In a data center’s cost structure, electrical losses are compounded rather than linear: a watt lost in a transformer or rectifier is a watt bought from the utility and also a watt of heat that the cooling plant must remove, at further energy cost. Small efficiency percentages at the front of the power chain therefore multiply through the operating budget over a facility life measured in decades.
The capital side may matter as much. Eliminating conversion stages means fewer step-down transformers, less associated switchgear, and less electrical room area — space that, in a market where construction timelines and grid connections are the binding constraints, converts directly into deployable IT capacity per site. For operators who cannot get more megawatts from their utility, extracting more usable compute from the megawatts already contracted is the highest-value optimization available.
None of that is quantified in the material accompanying this announcement. There is no published efficiency figure, no comparison baseline, no total-cost-of-ownership model and no pricing. The mechanism ABB describes is sound engineering and widely understood in the industry; the specific magnitude of the benefit is, on the evidence released so far, an assertion rather than a demonstrated result. Buyers should treat it accordingly and ask for the numbers.
A Crowded Answer to a Real Problem
ABB is not alone in reading the AI power problem this way. Medium-voltage UPS lines, solid-state transformer research, and the broader industry push toward higher-voltage direct-current distribution inside the rack are all attacking the same bottleneck from different points in the chain. Chip and system vendors have been pushing rack-level power architectures upward in voltage for similar reasons. These approaches are complementary rather than mutually exclusive — a facility could plausibly take medium voltage deep into the hall and then distribute at high-voltage DC to the racks.
The likely winners are hyperscale and large colocation operators building new capacity, where greenfield design allows the electrical architecture to be chosen rather than retrofitted, and where volume justifies training staff on medium-voltage practice. The likely losers are smaller enterprise sites and retrofit projects, which carry the complexity without the scale to amortize it. For ABB, the strategic value is defending a position in the electrification supply chain against competitors selling into the same buildings.
The risk to watch is supply chain rather than technology. Medium-voltage switchgear, transformers and related equipment have been in constrained supply across the electrical industry, with lead times that already shape data center schedules. A product that reduces the count of such components could ease that pressure; one that simply relocates demand to a differently scarce component would not. The announcement does not address lead times or manufacturing capacity.
Background
ABB is a long-established electrification and automation supplier whose portfolio spans switchgear, transformers, drives and power protection. Its HiPerGuard line is a medium-voltage UPS family aimed at large industrial and data center loads, positioned against the conventional approach of stepping utility power down to low voltage before it reaches protection equipment.
The market context is the rapid escalation of data center power requirements driven by AI workloads. As rack densities climb, operators face constrained utility connections, long grid interconnection queues and shortages of electrical equipment. That has pushed power architecture — historically a settled part of data center design — back into active competition among vendors, with voltage levels, conversion topologies and distribution schemes all under reconsideration.
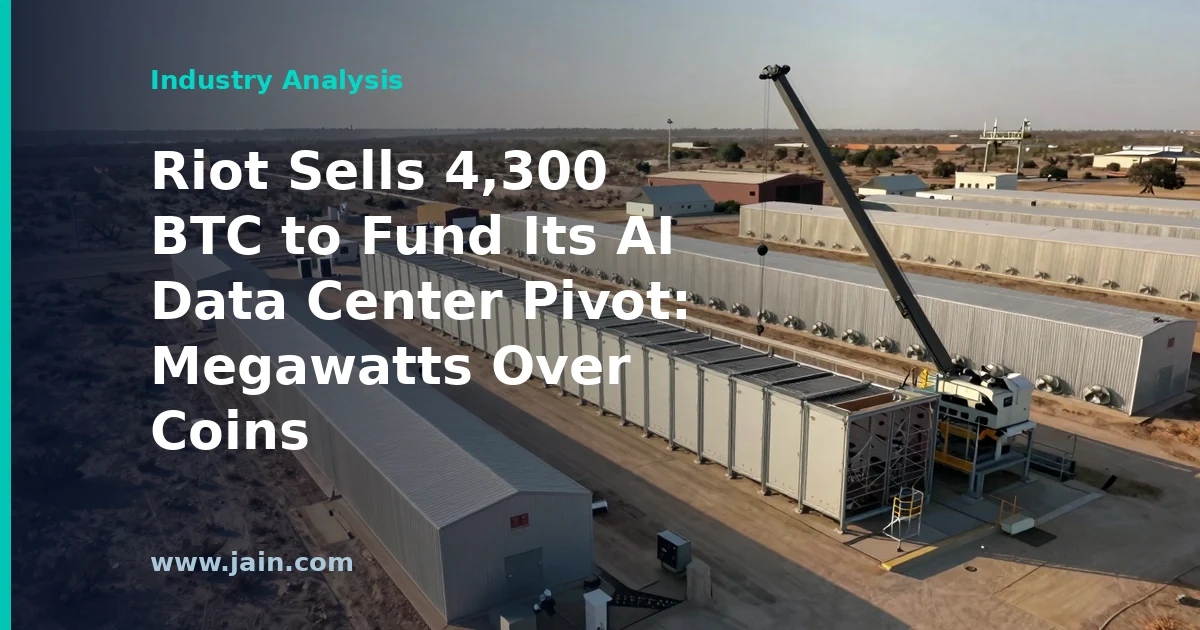
Bitcoin miner Riot has sold 4,300 BTC from its treasury to help fund the buildout of AI data center capacity, according to an April 20, 2026 report carried by TradingView. The sale converts a large slice of the company’s signature asset — its Bitcoin hoard — into construction capital for high-performance computing infrastructure.
Executive Summary
The reported transaction is notable less for its mechanics than for what it says about priorities. For years, large public Bitcoin miners treated their mined coins as a strategic reserve — a balance-sheet bet that holding Bitcoin would outperform selling it. Liquidating 4,300 BTC to pour concrete and energize halls for AI workloads inverts that logic: the scarce, appreciating asset Riot is now accumulating is powered data center capacity, not cryptocurrency.
If the report is accurate, Riot joins a growing cohort of miners redeploying their most valuable holdings — power contracts, land, substations, and now treasury coins — toward AI and high-performance computing (HPC) hosting, where demand from AI developers has made grid-connected megawatts one of the most sought-after assets in technology infrastructure.
From Strategic Reserve to Construction Budget
Bitcoin miners’ treasuries were long marketed to investors as a leveraged way to own Bitcoin: the company mines coins, holds them, and shareholders benefit if the price rises. Selling 4,300 BTC to fund a buildout is a deliberate break from that playbook. It says management believes a dollar invested in AI-ready data center capacity will return more than a dollar left sitting in Bitcoin — a striking assessment from a company whose core business is producing Bitcoin.
It is also a pragmatic financing choice. Data center construction is brutally capital-intensive, and the alternatives — issuing new shares, which dilutes existing holders, or borrowing, which adds interest costs and covenants — both carry real drawbacks. A treasury sale is the one funding source that requires no one else’s permission and creates no ongoing obligation. The trade-off is equally real: coins sold today cannot participate in any future Bitcoin rally, and shareholders who bought the stock as a Bitcoin proxy are now holding something different.
Megawatts Are the Scarce Asset Now
The deeper story is why miners are so well positioned for this pivot. AI training and inference clusters need enormous amounts of reliable electricity, and utility interconnections — the formal grid hookups that let a site draw hundreds of megawatts — can take years to secure. Bitcoin miners spent the last decade quietly assembling exactly those assets: large power contracts, energized substations, and industrial sites with cooling and fiber already in place.
That inheritance means a miner can offer AI tenants something hyperscale cloud builders often cannot: capacity that is available soon rather than after a multi-year interconnection queue. In that market, a company’s Bitcoin stack is incidental; its megawatts are the franchise. Riot converting coins into capacity is the cleanest expression yet of that repricing.
The Economics Behind the Pivot
Mining economics have tightened structurally. Bitcoin’s periodic “halvings” cut the block reward — the number of new coins miners earn — in half, which squeezes revenue per unit of computing power unless the Bitcoin price doubles to compensate. AI and HPC hosting offers a very different profile: multi-year contracts with creditworthy tenants, revenue in dollars rather than a volatile asset, and returns tied to utilization instead of a global hash-rate arms race.
But the pivot is not free money. AI hosting is a different business — different cooling densities, different reliability guarantees, different customers with demanding technical requirements — and miners must execute a conversion while incumbents like established colocation providers and hyperscalers expand aggressively. A miner that sells its Bitcoin, builds capacity, and then struggles to sign anchor tenants would have traded a volatile asset for an idle one. Execution, not vision, will decide who wins this transition.
Background
Riot Platforms grew into one of North America’s largest public Bitcoin miners by building power-hungry facilities in Texas, where it locked in substantial electricity capacity — an asset originally acquired to run mining rigs. Beginning around 2024, surging demand for AI computing collided with a shortage of grid-connected data center sites, and miners across the sector began converting or leasing their facilities to AI and high-performance computing tenants. Several of Riot’s peers struck high-profile hosting deals or announced conversions, establishing a template in which a miner’s power portfolio, rather than its coin production, drives its valuation. Riot’s reported treasury sale extends that industry-wide repositioning to the balance sheet itself.