Advertisement
- United States
- /
- Software
- /
- NasdaqGS:NBIS
Nebius Group (NasdaqGS:NBIS) Stock Could Be Overvalued After Sovereign AI Deal
SI

Reviewed by Bailey Pemberton
Nebius Group stock has almost doubled investors' money over the past five years, yet the current valuation checks lean toward an expensive profile rather than a clear bargain. After a rapid run in recent months, the key issue is whether recent excitement around its AI infrastructure positioning justifies paying up at these levels.
- Over the past 5 years, Nebius Group has delivered a total return of about 198%, which places recent gains against an already strong track record.
- The new partnership with Palantir on sovereign AI infrastructure can support confidence in Nebius Group's business opportunity, while execution risks around deploying large scale AI compute capacity may weigh on how much investors are willing to pay.
- Across a broad set of valuation checks, Nebius Group scores 0 out of 6, which points to a stock that screens as overvalued rather than an obvious bargain on traditional metrics.
For investors, the debate is whether Nebius Group's recent share price surge now builds in too much optimism relative to what the current fundamentals can justify.
Scan beyond Nebius Group's recent surge and line it up against hand picked AI infrastructure peers using our screener of 55 AI infrastructure stocks.
Does Nebius Group Look Pricey on Sales?
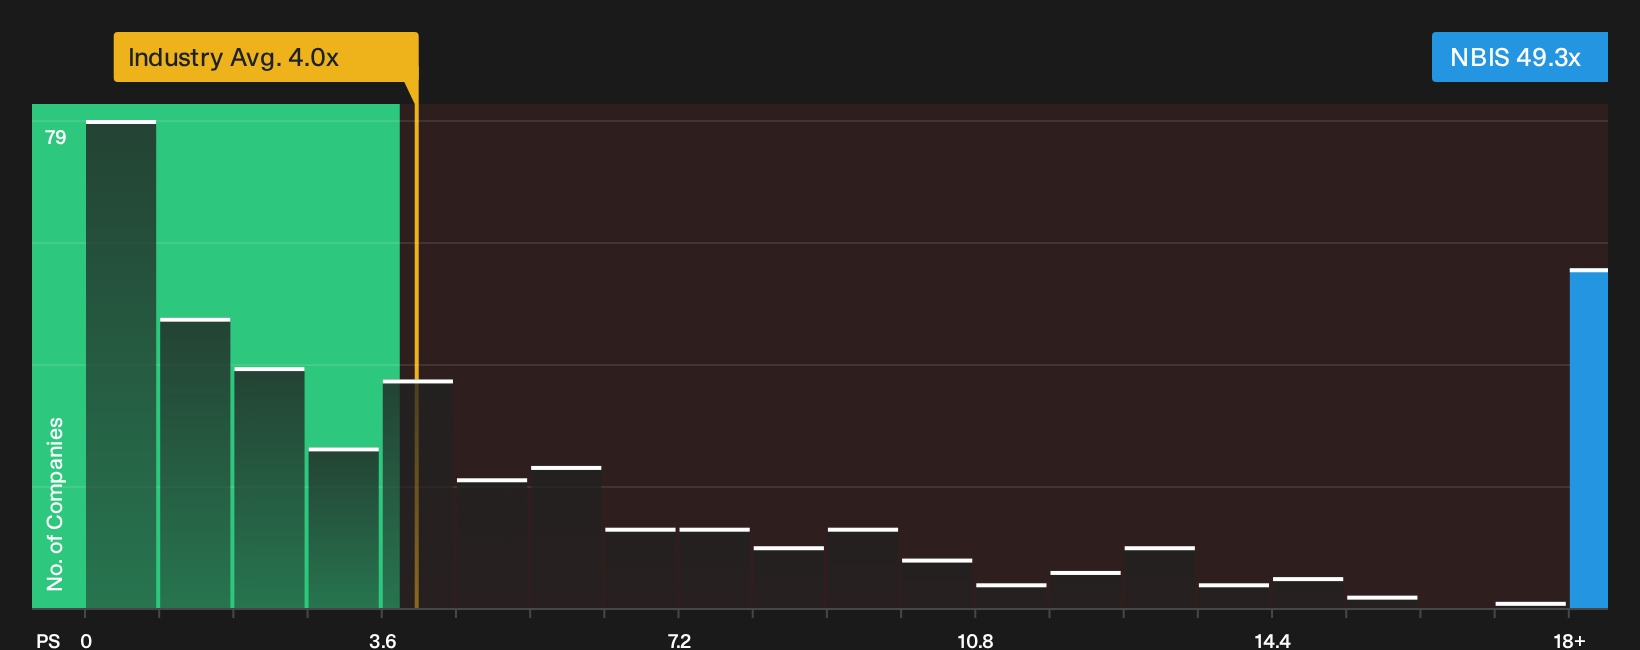
The P/S ratio suits Nebius Group because the business is still framed more by revenue scale and AI infrastructure demand than by traditional earnings metrics. On this lens, the stock trades on a P/S of 49.3x. That is far above the Software sector average of 4.0x and also well ahead of the peer group on 9.0x.
The tailored fair P/S multiple for Nebius Group, which factors in its growth profile, margins, size and risk, sits at 38.3x. The current 49.3x level is materially higher than that reference point, suggesting the share price already reflects a hefty premium. Despite the recent Palantir partnership anchoring a stronger commercial story around AI infrastructure, the valuation on sales still points to a rich entry tag compared with both sector norms and closer peers.
On the P/S yardstick, Nebius Group appears overvalued, with investors paying a substantial premium to both its fair multiple and to comparable software and AI infrastructure stocks.
See what the numbers say about this price — find out in our valuation breakdown.
The Nebius Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Nebius Group's valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today. Each Narrative presents Nebius Group's fair value as a thesis about the business that you can watch over time, instead of a one off snapshot, and they sit on the company's Community page.
Community views on Nebius Group now split sharply between a premium AI infrastructure winner and a capital heavy project that could struggle to earn its keep.
Bull case: 22% undervalued
"Nebius leverages rapid AI demand, global expansion, strategic partnerships, advanced technology, and strong funding to drive recurring revenue, margin growth, and long-term profitability..."
Read the full Bull Case to see why Nebius Group could be undervalued
Bear case: 103% overvalued
"Surging capital expenditures, as evidenced by the company's commitment to $2 billion in 2025 alone and a massive multi-year plan to secure 1 gigawatt of power by 2026, will likely drive down free cash flow and pressure net margins for years..."
Read the full Bear Case to see why Nebius Group could be overvalued
Do you think there's more to the story for Nebius Group? Head over to our Community to see what others are saying!
The Bottom Line
Nebius Group screens as overvalued on standard market multiples, with the premium underpinned more by expectations than by traditional checks. The crux is simple. Bulls see AI infrastructure demand and partnerships supporting that rich tag. Bears focus on heavy capital needs and the risk that future returns on that spend do not fully justify the current pricing. Your own view on how efficiently Nebius Group can turn large investments into durable cash generation is what really decides whether the premium looks acceptable or stretched.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we're here to simplify it.
Discover if Nebius Group might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
The most boring corner of the market just hit a 50-year low against stocks. History says that's when it's worth paying attention.

1815
p
pri_dlp7z
Supply-driven inflation breaks stocks and bonds at the same time. That is the one scenario commodities cover and nothing else does.
s
stefano_751bk
What the graphs says is that S&P 500 is just too expensive
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
84
About NasdaqGS:NBIS
Nebius Group
A technology company, engages in building full-stack infrastructure to service the global AI industry in the United States, the United Kingdom, and internationally.
High growth potential with slight risk.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2539.0% undervalued
183 followersusers have followed this narrative
0 commentsusers have commented on this narrative
28 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4933.5% undervalued
18 followersusers have followed this narrative
2 commentsusers have commented on this narrative
2 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k14.7% undervalued
20 followersusers have followed this narrative
0 commentsusers have commented on this narrative
4 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2538.9% undervalued
8 followersusers have followed this narrative
0 commentsusers have commented on this narrative
2 likesusers have liked this narrative
Recently Updated Narratives
RI

Rick_Orford on Sparc AI ·
What Overwatch's Ukraine Testing Means for SPARC AI Stock
Fair Value:CA$420.0% undervalued
0 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
JO


John_Eric on Grab Holdings ·
Grab Made $235 Million Last Quarter.Almost None of It Came From Operations.
Fair Value:US$5.944.9% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
LU


LunaRodas on ServiceTitan ·
TTAN | ServiceTitan, Inc.: What They Said vs. What They Did
Fair Value:US$74.629.3% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8325.5% undervalued
1399 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k47.6% undervalued
132 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32721.4% undervalued
1612 followersusers have followed this narrative
1 commentusers have commented on this narrative
15 likesusers have liked this narrative

