Advertisement
- United States
- /
- IT
- /
- NasdaqGS:CRWV
CoreWeave (CRWV) Stock Looks Cheap On Sales While Broader Checks Caution
SI

Reviewed by Bailey Pemberton
CoreWeave stock has slipped over the past month, yet valuation checks do not flag it as a clear bargain even though some multiples screen it as undervalued. With the share price also reacting to insider selling and balance sheet concerns, investors are weighing recent weakness against what they are paying for the growth story.
- The stock has fallen about 8.0% over the past month, which may make it look more attractive at first glance but does not automatically mean it is cheap.
- Expansion of CoreWeave’s AI cloud partnerships, such as the recent tie up with Rescale, can support revenue growth expectations. At the same time, rising debt worries and a large insider sale may keep some investors cautious about how much risk is already priced in.
- With a low value score of 2 out of 6, the broader checks suggest CoreWeave leans expensive rather than a clear bargain despite screening as undervalued on some multiples.
The stock’s next move may depend on whether CoreWeave’s current price already reflects these growth prospects and balance sheet risks, or if there is still room for a more attractive entry point.
Spot 55 AI infrastructure stocks that, like CoreWeave, are exposed to the AI buildout theme yet may offer different mixes of growth potential and balance sheet risk.Is CoreWeave Still Cheap on Sales?
P/S is a useful lens for CoreWeave because the company is still focused on scaling revenue while free cash flow and earnings remain under pressure. It helps you compare what the market is paying for each dollar of current sales against similar AI infrastructure and cloud stocks.
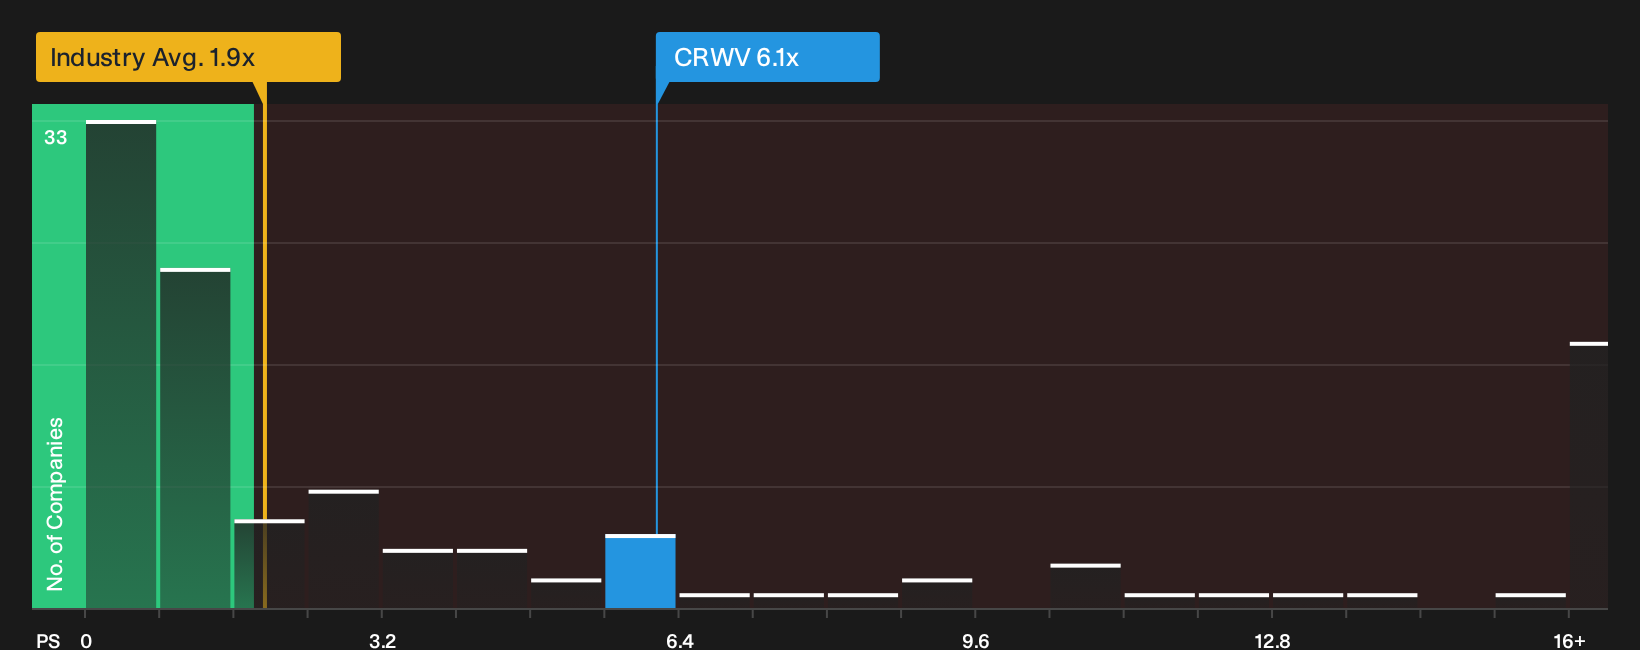
CoreWeave trades on a P/S of about 6.1x, which is above the broader IT sector average of 1.9x but below the peer group average of 10.7x. A P/S ratio of around 22.5x, based on its specific growth profile, margins, market position and risk, suggests the current valuation sits at a sizeable discount to what this framework would usually assign.
Despite recent focus on the insider sale and debt load, the stock currently reflects CoreWeave’s AI cloud opportunity at a level that appears lower than this tailored multiple indicates. That may appeal to investors who are comfortable with the balance sheet and execution risks tied to the AI buildout theme.
On the P/S multiple, CoreWeave stock currently screens as undervalued relative to the ratio implied by its business profile.
See what the numbers say about this price — find out in our valuation breakdown.
The CoreWeave Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this CoreWeave valuation puzzle leaves off and explain which paths for CoreWeave’s growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price, on Simply Wall St's Community page. Rather than relying on a single multiple or model, each narrative sets out its own fair value assumptions so you can later compare them with the company’s reported results.
The community is sharply split on CoreWeave, with one camp focused on backlog and AI demand and the other fixated on debt and hardware risk.
Bull case: 63% undervalued
"Explosive global adoption of AI across enterprises, AI-native startups and the public sector is driving sustained, demand led expansion of CoreWeave revenue, supported by a $55.6 billion revenue backlog and rapidly growing RPO that provide multi year visibility into top line growth and cash flows…"
Read the full Bull Case to see why CoreWeave could be undervalued
Bear case: 21% overvalued
"There is a concerning 'Capex Treadmill' here, every dollar of operational cash flow must be recycled immediately into the next generation of NVDA GPUs and optical networking to remain competitive…"
Read the full Bear Case to see why CoreWeave could be overvalued
Do you think there's more to the story for CoreWeave? Head over to our Community to see what others are saying!
The Bottom Line
CoreWeave screens as undervalued on its tailored P/S multiple, yet broader checks still point to a stretched valuation rather than a clear bargain. That tension reflects how much weight you put on the AI buildout opportunity versus concerns around debt, hardware intensity and execution. The crux for investors is whether revenue growth and margins can ultimately justify paying a premium multiple for a business with this balance sheet profile, or whether the current discount on sales proves to be a value trap rather than an entry point.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
You can copy Bill Ackman and buy Netflix. Knowing why you did is the hard part.

67
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
10
About NasdaqGS:CRWV
CoreWeave
Operates as a cloud infrastructure technology company in the United States.
Slight risk and slightly overvalued.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.5% undervalued
61 followersusers have followed this narrative
1 commentusers have commented on this narrative
15 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17014.4% undervalued
41 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8750.6% undervalued
39 followersusers have followed this narrative
2 commentsusers have commented on this narrative
17 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0929.9% undervalued
11 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
DU

duarte_EM on NVIDIA ·
NVIDIA — Selling the Picks & Shovels of the AI Build-Out
Fair Value:US$487.1553.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
ES

Ester on HHRG Berhad ·
HHRG Berhad Appoints Weststar Founder as Executive Chairman to Drive Strategic Growth
Fair Value:RM 0.3558.6% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
TH

THEGOATOFSTOCKS on Great Eastern Shipping ·
Great Eastern Shipping Will Amaze with a Future PE of 5.16x
Fair Value:₹614.61120.2% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS

oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28018.4% undervalued
376 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$7.31k72.8% undervalued
128 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
CU

CubanEros on Microsoft ·
A wonderful business at reasonable price.
Fair Value:US$419.9121.5% overvalued
223 followersusers have followed this narrative
0 commentsusers have commented on this narrative
9 likesusers have liked this narrative
