Advertisement
- United States
- /
- Software
- /
- NasdaqGS:NBIS
Nebius Stock Gets Palantir Partnership What Changes For Investors
SI

Reviewed by Sasha Jovanovic
- Nebius Group and Palantir Technologies announced a partnership in early September 2026 that brings Nebius’s AI-native cloud and compute infrastructure inside Palantir’s enterprise perimeter for eligible commercial clients, with plans to expand capacity through modular data centers at power-ready sites.
- The deal positions Nebius Group as Palantir’s preferred sovereign AI infrastructure partner, directly tying Nebius’s data centers and GPU stack to Palantir’s Sovereign AI Operating System and potentially influencing how enterprises think about owning AI models rather than renting access.
- The focus now turns to how Nebius becoming Palantir’s preferred sovereign AI infrastructure provider may reshape the broader investment narrative.
Nebius Group Investment Narrative Recap
For Nebius Group, the big picture you would need to buy into is simple. AI infrastructure keeps scaling, and this business keeps filling that demand with GPU clusters and a full-stack cloud platform. The Palantir agreement leans into that view by tying Nebius capacity directly to an enterprise grade AI operating system and by planning modular data centers at power ready sites. In the near term, the key swing factor remains execution on massive capex and utilization. The biggest risk still sits in pricing pressure and margin strain as competitors chase the same hyperscale AI budgets.
The fresh Palantir partnership looks most relevant here because it lives exactly at the intersection of Nebius Group’s biggest catalysts and worries. You get clearer demand visibility from being named preferred sovereign AI infrastructure partner for a large enterprise client base. You also get sharper scrutiny on reliability, regulatory compliance around data sovereignty, and returns on new GPU capacity. The deal does not remove concerns about high capital intensity or volatile earnings quality. It does, however, give investors more concrete proof points to watch around capacity deployment, customer adoption, and eventual gross margin behavior.
Even so, before treating Nebius as a straightforward AI infrastructure winner, it is worth pausing on one uncomfortable detail that could...
Read the full Nebius Group narrative to see the case behind these numbers.
Nebius Group's current analyst script points to revenues of $30.3b and earnings of $2.4b by 2029, built on a very high 181.9% yearly revenue growth assumption. That profile implies earnings today of $42.4m would need to climb by roughly $2.36b to hit the 2029 consensus target.
Nebius Group's forecasts hold fair value at $312.67 against a $240.35 share price, representing a 30% upside to its current price that could narrow quickly.
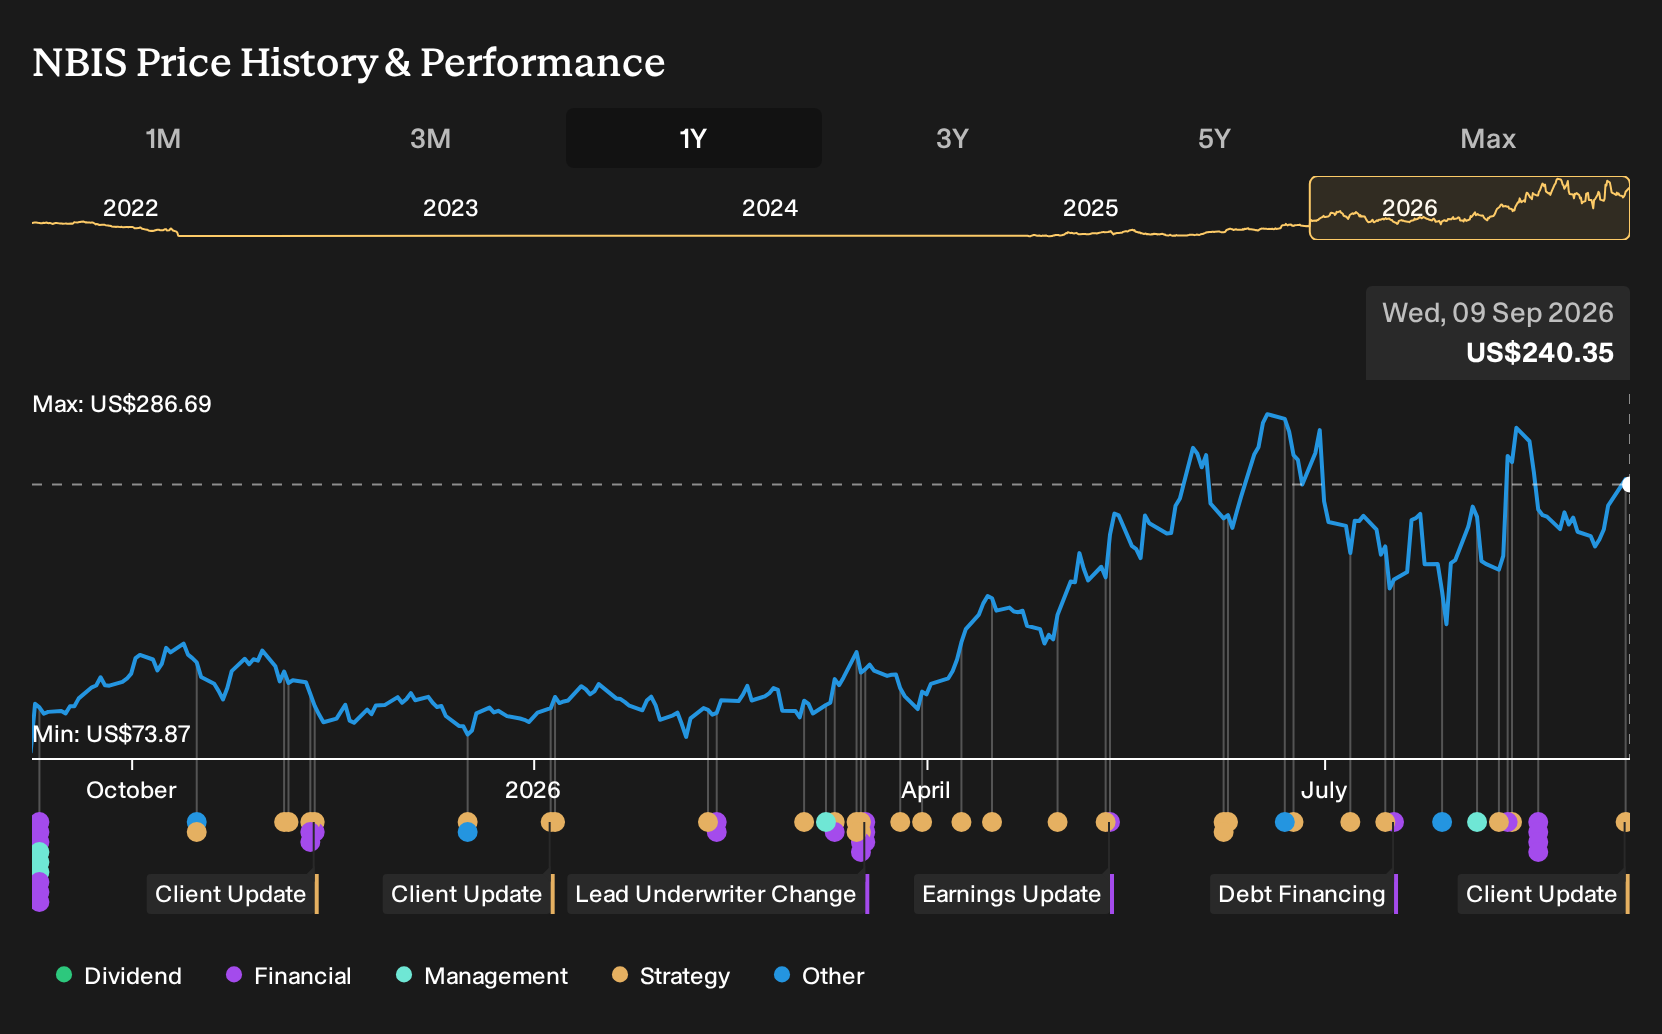
Exploring Other Perspectives
One alternative view leans into capacity risk. Some of the most optimistic Nebius Group analysts already pencilled in revenue of $48.5b and earnings of $1.1b by 2029, well above the $30.3b revenue and $2.4b earnings path in the consensus script. Those forecasts were set before this Palantir sovereign AI deal, so you should expect opinions to shift and diverge further as the partnership impact becomes clearer.
If you want to see how other investors frame Nebius Group’s price, check the 16 other fair value estimates for Nebius Group for more context.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Nebius Group research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Nebius Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nebius Group's overall financial health at a glance.
Looking for more Nebius Group style investment ideas?
If the Nebius Group story has you thinking about how AI infrastructure, balance sheet strength, and long term compounding might fit into your own portfolio, it can help to scan a wider field of stocks using the Simply Wall St Screener.
- If you want potential mispricing first, start with companies that screen as attractively valued through the 31 high quality undervalued stocks and compare their fundamentals to Nebius Group's profile.
- If resilience matters more to you than headlines, focus on businesses that pass tight risk filters in the 10 resilient stocks with low risk scores and see which ones match your tolerance.
- If financial strength is your anchor, look through the list of solid balance sheet and fundamentals (24 results) to find firms with cleaner leverage and liquidity than many growth focused peers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we're here to simplify it.
Discover if Nebius Group might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
Oracle has $638 billion of orders it can't fill yet. Tonight tells us how much it's costing to get ready.
97
s
sean_3pk06
Sixty-eight percent gross margin business is buying its way into a thirty-five percent gross margin business, and revenue growth is the metric everyone is watching.
d
devon_jd150
This is important about Oracle. Nvidia went to six of the biggest asset managers on earth to make sure someone else held this risk. Oracle just borrowed the money and held it itself.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
84
About NasdaqGS:NBIS
Nebius Group
A technology company, engages in building full-stack infrastructure to service the global AI industry in the United States, the United Kingdom, and internationally.
High growth potential with slight risk.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2536.2% undervalued
186 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4934.6% undervalued
38 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k15.9% undervalued
27 followersusers have followed this narrative
0 commentsusers have commented on this narrative
8 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.2% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
PR


prajeeshprathap on Clean Harbors ·
The Environmental Infrastructure Compounder Built for Decades of Growth
Fair Value:US$3509.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
LU


LunaRodas on Vince Holding ·
VNCE | Vince Holding Corp.: What They Said vs. What They Did
Fair Value:US$4.8431.8% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
FR


FRAGMENTS on America's Car-Mart ·
America’s Car-Mart Trades Around $1.50. Book Value Is $45.20. Who Owns the Recovery?
Fair Value:US$2.7546.4% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8326.1% undervalued
1407 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32722.8% undervalued
1622 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.7% undervalued
1594 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative

