
Advertisement
- United States
- /
- Software
- /
- NasdaqCM:CLSK
Is CleanSpark (CLSK) A Bargain On Texas Power Progress And Its Georgia Lease?
CleanSpark (CLSK) is back in focus after ERCOT classified 885 MW of its Texas power load across base load and studied categories, while the firm also signed a 20-year lease for a 175 MW Georgia data center campus.
Recent attention on CleanSpark has come against a mixed backdrop, with the share price down 22.33% over the past 90 days but up 11.11% over 30 days and higher again year to date by 10.82% as investors weigh new capacity news against earlier volatility. At the current US$12.80 share price, the 1-year total shareholder return of 25.49% and very large 3-year total shareholder return above 7x indicate that momentum has been positive over longer periods. At the same time, short term swings reflect changing expectations around growth projects and risk in Bitcoin mining infrastructure.
Scan beyond CleanSpark and size up other power-hungry infrastructure plays with the hand picked 39 power grid technology and infrastructure stocks.
CleanSpark now trades at US$12.80 while the average analyst estimate sits near US$23.81, creating a wide gap after a choppy few months. Does fair value lie closer to the screen price or the spreadsheet range?
Most Popular Narrative: 46.2% Undervalued
CleanSpark's most followed valuation storyline points to a fair value of about $23.81 against the recent $12.80 share price, framing a wide gap that rests on long term lease economics, power capacity and higher quality data center style cash flows.
The analysts have a consensus price target of $23.81 for CleanSpark based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $857.1 million, earnings will come to $98.0 million, and it would be trading on a PE ratio of 84.4x, assuming you use a discount rate of 10.1%.
Want to see what sits behind that rich future earnings multiple for CleanSpark? The fair value hinges on a specific revenue path, margin lift and share count profile that sharply contrasts with its current loss making status and modest top line growth today.
Result: Fair Value of $23.81 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the CleanSpark story depends heavily on Bitcoin economics and capital intensive expansion. As a result, weaker crypto pricing or tougher funding conditions could quickly challenge that upbeat valuation path.
Find out about the key risks to this CleanSpark narrative.
Another View: CleanSpark Through Sales Multiples
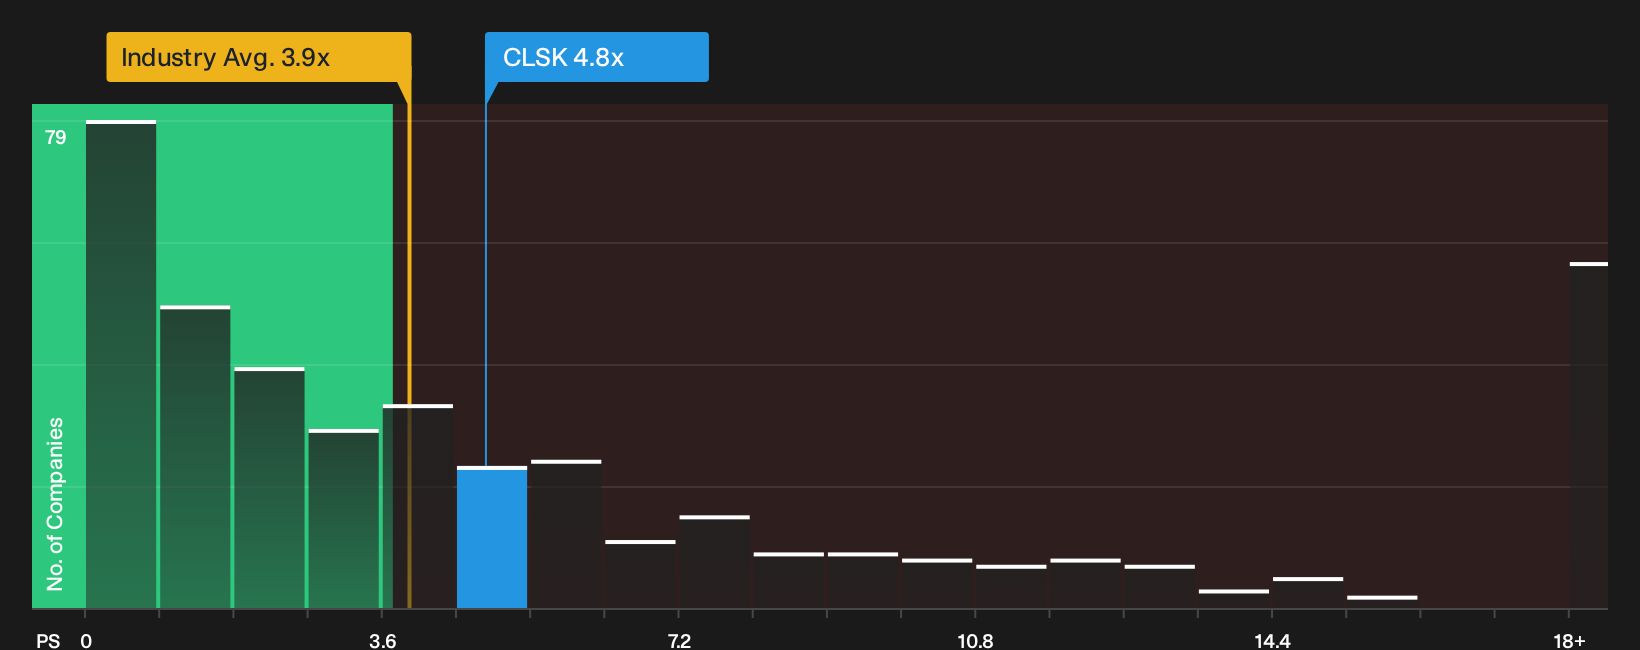
That bullish CleanSpark narrative leans on future earnings and a rich P/E. A quick reality check on today's P/S tells a different story. The stock trades around 4.8x sales, above the US Software average near 3.9x, and well above a fair ratio estimate of 2.6x.
This gap suggests investors are already paying a premium versus the broader sector, while the fair ratio points to a level the market could potentially move toward over time. The shares do appear cheaper than a 6.6x peer average, which raises a simple question: Is CleanSpark priced for quality, or is it primarily benefiting from a popular theme?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the recent CleanSpark optimism really outweighs the concerns? Act quickly, review the numbers, and weigh both sides through the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond CleanSpark?
If CleanSpark has your attention, consider broadening your opportunity set with a few targeted screens that highlight different types of companies and risk profiles.
- Explore potential mispricing and look for quality at a discount by scanning the 33 high quality undervalued stocks.
- Focus on resilience and aim for greater peace of mind by sorting through the 11 resilient stocks with low risk scores.
- Identify strong finances that may support future plans by filtering companies in the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
Oracle has $638 billion of orders it can't fill yet. Tonight tells us how much it's costing to get ready.
117
s
sean_3pk06
Sixty-eight percent gross margin business is buying its way into a thirty-five percent gross margin business, and revenue growth is the metric everyone is watching.
d
devon_jd150
This is important about Oracle. Nvidia went to six of the biggest asset managers on earth to make sure someone else held this risk. Oracle just borrowed the money and held it itself.
 Andrew Legget
Market Insights
Are social media stocks the new Big Tobacco?

Greater regulatory scrutiny is catching up with digital platforms, posing a rising risk for social media stocks. But as Big Tobacco discovered, that's not always a bad outcome for shareholders.
00
About NasdaqCM:CLSK
CleanSpark
Operates as a bitcoin mining company in the Americas.
Low risk and slightly overvalued.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2540.0% undervalued
186 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4937.2% undervalued
38 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k17.2% undervalued
27 followersusers have followed this narrative
0 commentsusers have commented on this narrative
8 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.7% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
IS

isidrohg on Amphenol ·
Amphenol Wins Whether The Rack Goes Copper Or Optical — And That Is The Point
Fair Value:US$102.3521.6% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
IS

isidrohg on Vertiv Holdings Co ·
Every Watt Needs Cooling — Vertiv Is Buying Its Way Upstream To The Real Bottleneck
Fair Value:US$370.8933.1% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
CH

chad_5q9ob on Pentech Holdings Berhad ·
上市后的PENTECH规模已经够大,下一步的发展引擎是?
Fair Value:RM 0.351.4% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8327.9% undervalued
1408 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32723.0% undervalued
1624 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.3% undervalued
1597 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative

