Advertisement
- United States
- /
- Software
- /
- NasdaqCM:CLSK
Bitcoin Production Update At CleanSpark Stock Has Changed Its Investment Story
SI

Reviewed by Sasha Jovanovic
- CleanSpark reported unaudited bitcoin production of 593 coins for August 2026 and 4,903 coins for the year through August 31.
- The latest output figures give investors a fresh read on how CleanSpark is converting its mining footprint and energy access into actual bitcoin volume.
- With August production of 593 bitcoin now on the table, this update may influence how investors view CleanSpark's broader investment narrative.
Scan how CleanSpark's latest production update compares to peers by lining it up against hand-picked 19 cryptocurrency and blockchain stocks that are also tied directly to bitcoin and blockchain activity.
CleanSpark Investment Narrative Recap
To own CleanSpark, you need to believe its power efficient bitcoin mining footprint and access to energy can keep turning into consistent coin output, even as the industry evolves. The August tally of 593 bitcoin and 4,903 year to date gives you a clean read on current throughput. The near term swing factor still looks like how efficiently new capacity and power contracts can translate into mined volume.
The bigger operational risk right now sits around cost discipline in a capital hungry, single commodity business. This latest update is helpful operational color but not a thesis changing data point on its own.
The most relevant recent data point here is the production disclosure itself. CleanSpark reported 593 bitcoin for August 2026 and 4,903 for the year through August 31. Those figures help you gauge whether the fleet and energy strategy referenced in prior materials is actually turning into mined coins. They also feed directly into revenue potential, cash generation, and the room management has to fund further expansion without leaning harder on equity or higher cost debt.
Analyst tools such as the Zacks Rank or brokerage averages sit in the background. The operational story still turns on how reliably CleanSpark can keep that production engine running against volatile bitcoin pricing and periodic hardware upgrades.
Yet one unresolved issue still hangs over this otherwise straightforward production story...
Read the full CleanSpark narrative to see the case behind these numbers.
CleanSpark's narrative projects US$857.1 million revenue and US$98.0 million earnings by 2029. That profile assumes 8.1% yearly revenue growth and an earnings increase of roughly US$1.1b from a loss of US$1.0b today.
CleanSpark's forecasts put fair value at $23.81 against a $13.28 share price, a 79% upside to its current price that could narrow quickly.
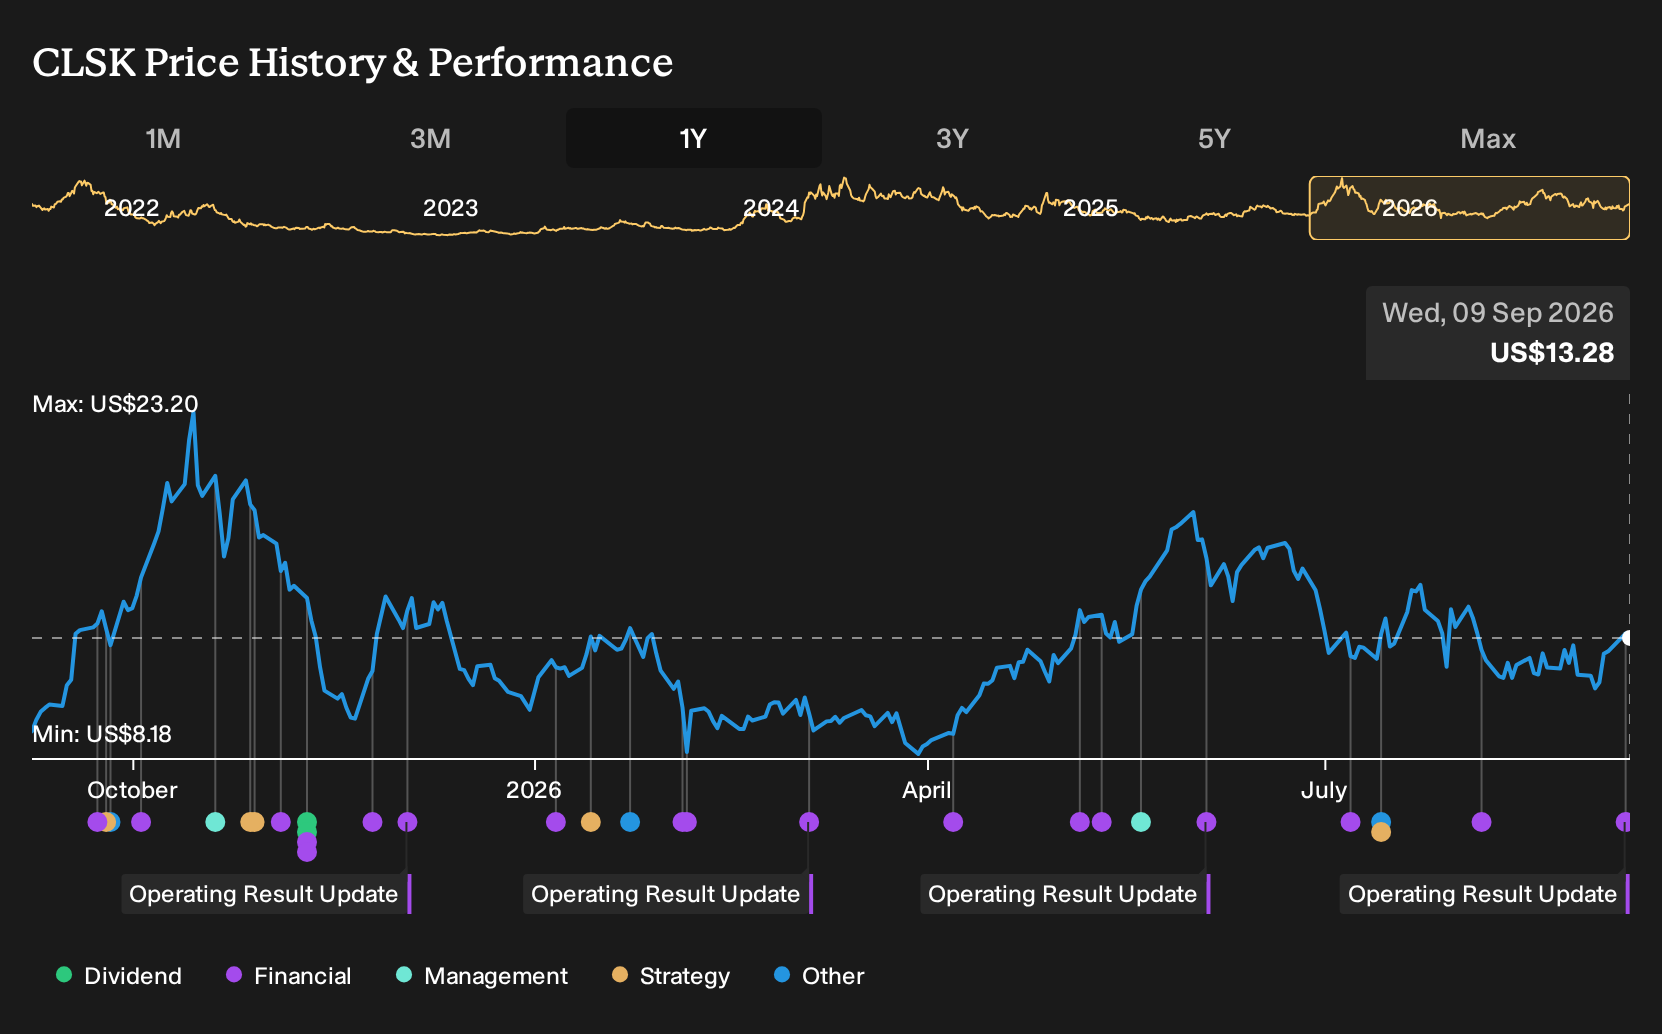
Exploring Other Perspectives
Some analysts frame regulatory risk very differently. Where the baseline view leans on policy support, the lowest forecasts assume tighter rules could slow CleanSpark, with revenue nearer US$722.3 million and earnings around US$83.6 million by 2029. Those estimates were set before this August production report, so opinions may shift as you review both narratives.
If you want to see how other investors are framing CleanSpark's value, compare this narrative against 4 other fair value estimates for CleanSpark.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CleanSpark research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CleanSpark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate CleanSpark's overall financial health at a glance.
Looking For More Investment Ideas Beyond CleanSpark?
If you want to broaden your watchlist beyond CleanSpark, it can help to scan for other businesses that share traits you care about such as valuation support, balance sheet strength, or relatively lower risk profiles. The Simply Wall St Screener offers several starting points that you can use as a jumping-off tool for building that wider universe.
- If valuation discipline is your first filter, start with companies that currently look mispriced relative to their quality using the 49 high quality undervalued stocks.
- For readers who care most about financial resilience, focus on companies with healthier leverage and liquidity by checking the list of solid balance sheet and fundamentals (24 results).
- If capital preservation sits high on your list, consider stocks that screen with lower overall risk profiles through the 80 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
Razors, glasses, mattresses, all toppled by direct-to-consumer upstarts. Beer wasn't. A 90-year-old law is why.
910
s
sarah_c5otv
Forget beer. Wine volume is down the drain and it has direct-to-consumer shipping in most states. The category with the freest distribution is falling fastest.
artoflosing
Funny. Beer sales aren't growing anymore. A toll booth in a shrinking market may not be a great choice to invest.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
84
About NasdaqCM:CLSK
CleanSpark
Operates as a bitcoin mining company in the Americas.
Low risk and slightly overvalued.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2536.2% undervalued
187 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4934.6% undervalued
32 followersusers have followed this narrative
2 commentsusers have commented on this narrative
9 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k15.9% undervalued
24 followersusers have followed this narrative
0 commentsusers have commented on this narrative
7 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.2% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
FU


FundamentalFlow on Vistra ·
US Energy Giant: PowerHouse Of The Future Of AI
Fair Value:US$299.9849.6% undervalued
23 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
MA


MarkoVT on ANYCOLOR ·
Near zero debt, Japan centric focus provides future growth
Fair Value:JP¥4.05k29.6% undervalued
8 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
TH

The_Dutch_Investors on ASML Holding ·
ASML is Perhaps Europe’s Best Business, But Not at Any Price.
Fair Value:€1.01k48.3% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8326.1% undervalued
1402 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32722.8% undervalued
1618 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.7% undervalued
1593 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
