
Advertisement
- United States
- /
- Software
- /
- NasdaqGS:HUT
Hut 8 (HUT) Could Be 39% Undervalued As AI Data Center Deals Recast Its Story
Hut 8 (HUT) is trying to reinvent itself after years as a Bitcoin miner, with its Texas data center for Nvidia, tied to Anthropic’s reported US$35b computing deal, putting that shift firmly in focus.
Investors have reacted quickly to Hut 8’s AI pivot, with the stock posting a 1-day share price return of 6.36% and a 7-day share price return of 28.26%. This is despite the 90-day share price return declining 5.86% and the 1-year total shareholder return being very large at 239.56%.
Scan beyond Hut 8 and evaluate other AI infrastructure plays with the curated list of 55 AI infrastructure stocks that are already drawing serious attention from the market.
Bulls view Hut 8 as an AI landlord with multi year Nvidia and Anthropic linked leases, while bears focus on a loss making core and Bitcoin baggage. Which story does the current valuation lean toward?
Most Popular Hut 8 Narrative: 38.5% Undervalued
Hut 8's most widely followed narrative pegs fair value around $161.78 per share, compared with the last close at $99.49. This frames a valuation gap for investors to assess.
The Power First strategy, featuring sizable pipeline origination (10.8 GW under diligence, 3.1 GW under exclusivity) and dual-purpose sites for both Bitcoin mining and AI compute, provides scalability and flexibility to benefit from rising institutional adoption of digital assets and accelerating demand for clean energy powered blockchain infrastructure, bolstering future revenue and earnings growth.
Read the complete narrative. Read the complete narrative.
Want to understand why this framework lands on a much higher fair value for Hut 8 than the market price implies right now? The core thesis leans on projected revenue expansion, a shift in margins from losses toward profitability, and a future earnings multiple that sits above typical software peers. It examines which growth assumptions, profitability path and discount rate combine to support that number and how sensitive the outcome is to execution on the AI lease pipeline.
Result: Fair Value of $161.78 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the narrative around Hut 8 can shift quickly if Bitcoin driven earnings remain weak or if large AI tenants delay or renegotiate those long dated leases.
Find out about the key risks to this Hut 8 narrative.
Another View On Hut 8 Using Sales Multiples
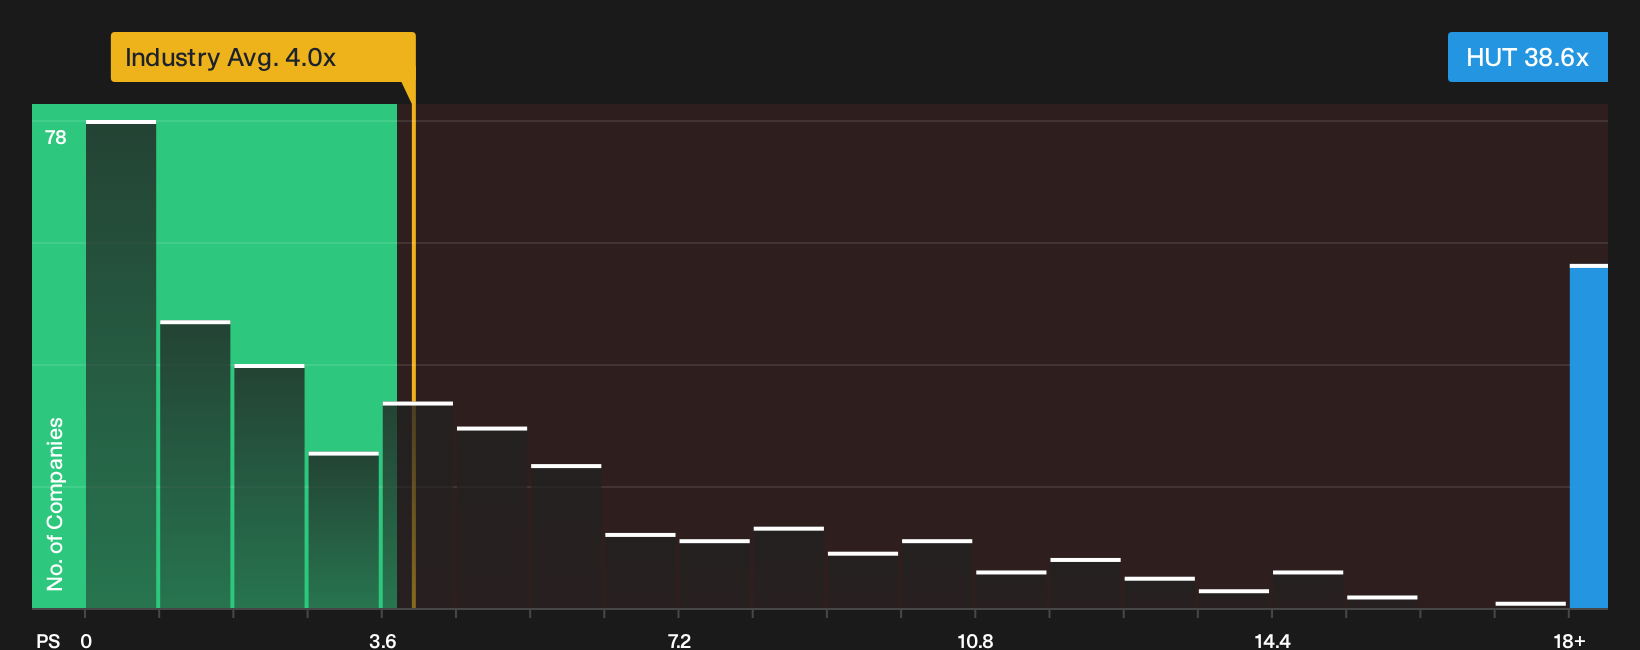
The first Hut 8 narrative leans on analyst forecasts to argue the stock looks 38.5% undervalued against a $161.78 fair value. A simple P/S lens tells a very different story. Hut 8 trades on a P/S of 38.6x versus 4x for the US Software sector and 1.6x for peers, while the fair ratio sits at 14.7x. That gap points to a lot of expectation already in the price. The key question is whether you think those expectations are realistic or overly generous.
To pressure test whether this richer sales multiple feels justified for your own portfolio, it helps to see what the numbers say in a full breakdown first, then decide how much valuation risk you are comfortable carrying. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Hut 8 story today. If you want a sharper read on risk and opportunity, go straight to the source data and pressure test the full picture for yourself with the 1 key reward and 4 important warning signs.
Looking for more Hut 8 style investment ideas?
If the Hut 8 story has sharpened your thinking, you could use that momentum and scan other opportunities before the market prices them more fully.
- Target potential mispricings by checking the 49 high quality undervalued stocks that combine quality fundamentals with prices the market has not fully rewarded yet.
- Prioritise resilience and focus on stability by reviewing the 83 resilient stocks with low risk scores built around businesses with stronger risk profiles.
- Look for early stage opportunities with real substance by scanning the 17 high quality undiscovered gems that most investors are not watching closely yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we're here to simplify it.
Discover if Hut 8 might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Access Free AnalysisHave feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
The most boring corner of the market just hit a 50-year low against stocks. History says that's when it's worth paying attention.

1313
p
pri_dlp7z
Supply-driven inflation breaks stocks and bonds at the same time. That is the one scenario commodities cover and nothing else does.
s
stefano_751bk
What the graphs says is that S&P 500 is just too expensive
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
74
About NasdaqGS:HUT
Hut 8
Operates as an energy infrastructure platform that integrates power, digital infrastructure, and compute at scale to fuel energy-intensive use cases in the United States and Canada.
Slight risk with limited growth.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.577.0% undervalued
75 followersusers have followed this narrative
1 commentusers have commented on this narrative
18 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4933.5% undervalued
13 followersusers have followed this narrative
1 commentusers have commented on this narrative
2 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k14.7% undervalued
15 followersusers have followed this narrative
0 commentsusers have commented on this narrative
1 likeusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2538.9% undervalued
6 followersusers have followed this narrative
0 commentsusers have commented on this narrative
1 likeusers have liked this narrative
Recently Updated Narratives
CA


Cannibal_Stocks on Transocean ·
The Last Drillship Was Built Years Ago. Transocean Just Bought a Third of the Ones That Exist
Fair Value:US$936.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
HE


HedgeY on Salesforce ·
Salesforce: From Selling Seats to Selling Governed Work
Fair Value:US$294.9315.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
FR


FRAGMENTS on Cable One ·
Cable One Trades in the Mid-$20s. The Network Still Makes Money. The Debt Decides Who Gets It.
Fair Value:US$17086.5% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8325.5% undervalued
1392 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32721.4% undervalued
1611 followersusers have followed this narrative
1 commentusers have commented on this narrative
15 likesusers have liked this narrative
JO


John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k47.6% undervalued
132 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative


