
Advertisement
- United States
- /
- Software
- /
- NasdaqGS:CORZ
Core Scientific (CORZ), Why Is Its Latest Update Drawing Attention?
What Core Scientific’s New Credit Facilities Mean For Investors
Core Scientific (CORZ) has secured $600 million in senior secured credit facilities, a move that increases liquidity and reshapes its capital structure at a time when digital asset infrastructure is evolving quickly.
The package combines a $100 million revolving credit facility with a $500 million letter of credit facility. For you as an investor, the key point is not just the size of the financing but also how it changes the company’s access to cash and support for future projects.
Management expects the facilities to release about $300 million of restricted cash. That is a sizeable shift in available funds that could influence how Core Scientific approaches working capital, power agreements and potential growth initiatives in the coming years.
Over the past year Core Scientific’s share price has been volatile, with the 7 day share price return of 8.36% contrasting with a 30 day decline of 14.85% and a 90 day decline of 34.11%. At the same time, the 1 year total shareholder return of 31.35% points to stronger longer term momentum around the stock.
Spot opportunities around Core Scientific’s financing move by comparing it with a curated group of 21 cryptocurrency and blockchain stocks that are also tied to digital asset infrastructure and blockchain exposure.Bulls see Core Scientific’s new $600 million credit package as fuel for growth, while bears focus on recent share price weakness and ongoing losses. Which side does the valuation lean toward next?
Most Popular Narrative: 51.8% Undervalued
The most followed narrative on Core Scientific pegs fair value at $37.13 per share compared with the last close of $17.89, which frames the credit facilities against a much higher long term earnings story.
The analysts have a consensus price target of $37.12 for Core Scientific based on their expectations of its future earnings growth, profit margins and other risk factors.
We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Analysts are not just guessing. Their fair value hinges on steep revenue expansion, a swing from heavy losses to profits and a richer earnings multiple than the wider software sector. Curious how those ingredients combine to support a value that is more than double today’s price?
Result: Fair Value of $37.13 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
However, Core Scientific’s story can shift quickly if its reliance on large counterparties like CoreWeave and AMD is tested, or if execution on new HPC capacity falls behind expectations.
Find out about the key risks to this Core Scientific narrative.
Another View On Core Scientific’s Valuation
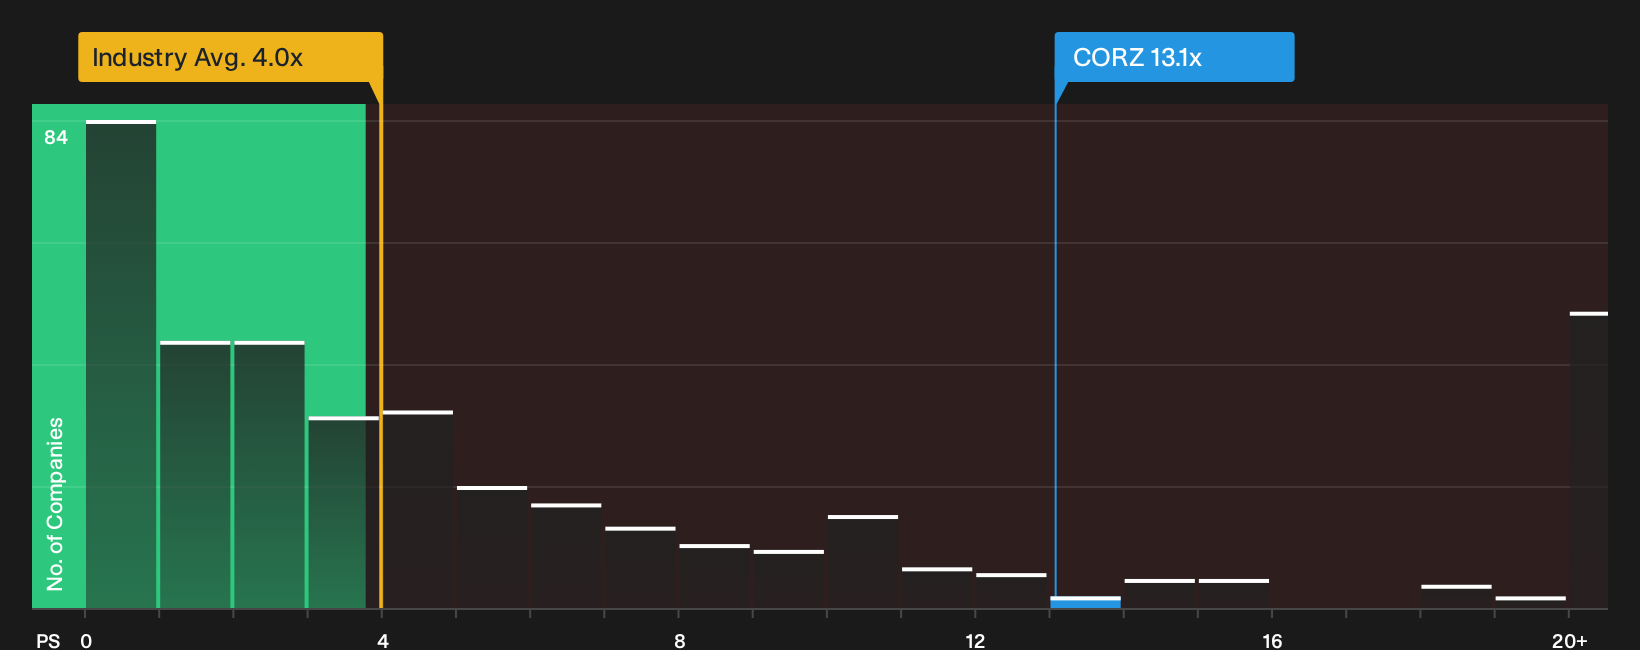
There is a clear gap between the analyst fair value on Core Scientific and what the market is paying today. On a P/S of 13.1x versus 4x for the US Software industry and 2.4x for peers, and a fair ratio of 6.1x, the stock screens as expensive. Is the growth story strong enough to justify paying more than double that fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of optimism and concern around Core Scientific is clear, so act quickly by reviewing the underlying numbers, risks and potential rewards for yourself. To see the balance of sentiment in one place, take a closer look at the 1 key reward and 3 important warning signs.
Looking For More Investment Ideas Beyond Core Scientific?
If you only focus on Core Scientific, you might miss other compelling setups. Use the Simply Wall Street Screener to uncover fresh opportunities that fit your style.
- Target potential mispricing by scanning a 47 high quality undervalued stocks that combine solid fundamentals with attractive valuations.
- Strengthen portfolio resilience by focusing on a list of solid balance sheet and fundamentals (53 results) that can better handle financial pressure.
- Spot early opportunities by reviewing a 17 high quality undiscovered gems before they appear on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
You can copy Bill Ackman and buy Netflix. Knowing why you did is the hard part.

1214
f
frank_ub3n0
Netflix case is interesting. The scariest competitor is the one that does not need to make money. Amazon can run video at a loss forever because it is really a Prime retention tool with a content budget attached. On the other hand there is Youtube.
a
arjun_dyig0
Pershing Square hasn't beaten the S&P over the last five years, though the long-run record is genuinely good. I like Ackman as a person. I enjoy listening to Ackman and that's about where it ends for me.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
31
About NasdaqGS:CORZ
Core Scientific
Provides infrastructure for high-density colocation services and digital asset mining in the United States.
High growth potential with low risk.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.9% undervalued
66 followersusers have followed this narrative
1 commentusers have commented on this narrative
17 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17016.9% undervalued
48 followersusers have followed this narrative
3 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8748.8% undervalued
48 followersusers have followed this narrative
2 commentsusers have commented on this narrative
19 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0931.0% undervalued
12 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
MA


MarkoVT on ANYCOLOR ·
Near zero debt, Japan centric focus provides future growth
Fair Value:JP¥4.05k26.3% undervalued
8 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
MO


MontyNorman on Platform Group SE KGaA ·
Unbelievable numbers. Be very careful!
Fair Value:€0.1915.0% overvalued
6 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
CL


Clive_Thompson on Novogenia ·
Novogenia: A High-Risk, Asset-Backed Micro-Cap With Significant Optionality
Fair Value:€16.762.0% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28017.7% undervalued
373 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k46.2% undervalued
130 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
AN

AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8323.9% undervalued
1378 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
Trending Discussion
DA
daniel_uvswg on Oncolytics Biotech ·
Thank you for the detailed backdown regarding this company and its stock. I think given the data and looking to be optimistic I would likely believe that it's no unbelievable to assume that the stock price could go to the ~$3 mark. Even at that level it's not a bad deal especially coming from sub $1 stock at the moment.
1
|0