Advertisement
- United States
- /
- Software
- /
- NasdaqGS:CORZ
Is Core Scientific (CORZ) Stock Too Expensive After Its 12% Drop?
SI

Reviewed by Bailey Pemberton
Core Scientific stock has given investors a rough month, with the share price under pressure while broader valuation checks suggest the company does not screen as a bargain on usual metrics. For anyone tracking mining-focused crypto infrastructure, the current setup raises questions about how much optimism is already embedded in the US$17.37 share price.
- Over the past 30 days, Core Scientific has fallen 12.1%, which points to a period where expectations have cooled after earlier gains this year.
- Future returns for the business may hinge on how efficiently it can run its mining fleet and manage energy and capital costs, since these factors can heavily influence cash generation in a volatile Bitcoin pricing backdrop.
- The stock scores 0 out of 6 on a broader set of valuation checks, which signals that Core Scientific does not look like a clear bargain based on this framework.
The issue now is whether the recent pullback has moved Core Scientific closer to a reasonable entry point or if the shares still lean expensive given the risks around its cash flows and cost base.
Scan beyond Core Scientific and compare it with 33 high quality undervalued stocks, which pair cleaner balance sheets with cash flows that may better justify their current market prices.
Is Core Scientific Getting Expensive on Sales?
P/S is often a cleaner lens for Core Scientific because profitability and free cash flow are currently under pressure, while revenue is easier to observe and compare.
On this yardstick, Core Scientific trades at roughly 12.7x sales. The broader software industry sits closer to 3.9x, and peers average about 2.2x. The fair P/S ratio implied by the model is 6.1x, which is roughly half of where the stock currently changes hands, so the market is attaching a heavy premium to each dollar of Core Scientific revenue.
That gap suggests investors are already paying up for the crypto mining footprint and potential operating improvements rather than buying a discounted top line today. Anyone evaluating Core Scientific stock through this lens is not seeing a bargain multiple, but a valuation that assumes favorable outcomes on execution and Bitcoin economics.
On the P/S metric, Core Scientific currently screens as overvalued relative to both benchmarks and the modelled fair ratio.

See what the numbers say about this price — find out in our valuation breakdown.
The Core Scientific Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle leaves off for Core Scientific and explain which assumptions on growth, profitability and earnings would need to hold for the current share price to appear meaningfully higher or lower in hindsight. Each scenario is used as a thesis about Core Scientific's business that you can track over time rather than a static fair value snapshot. These can be found on Simply Wall St's Community page for investors who want that extra layer of context.
One of the top community narratives on Core Scientific: 53% undervalued
"Core Scientific secured a major HPC contract with CoreWeave, with a total revenue potential of $8.7 billion over a 12-year term..."
Read one of the top narratives on Core Scientific
Do you think there's more to the story for Core Scientific? Head over to our Community to see what others are saying!
The Bottom Line
Core Scientific currently looks overvalued on simple sales multiples, with the share price asking investors to pay a premium for each dollar of revenue. The broader valuation checks are weak, so the market is already baking in a constructive story on execution and Bitcoin economics rather than offering a clear discount. For you, the key question is whether Core Scientific can translate its crypto infrastructure and contracts into durable cash generation that eventually backs up this richer tag, or whether the current premium leaves little margin for error if operating progress stalls.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
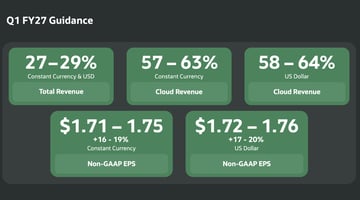
Oracle has $638 billion of orders it can't fill yet. Tonight tells us how much it's costing to get ready.
137
s
sean_3pk06
Sixty-eight percent gross margin business is buying its way into a thirty-five percent gross margin business, and revenue growth is the metric everyone is watching.
d
devon_jd150
This is important about Oracle. Nvidia went to six of the biggest asset managers on earth to make sure someone else held this risk. Oracle just borrowed the money and held it itself.
 Andrew Legget
Market Insights
Are social media stocks the new Big Tobacco?

Greater regulatory scrutiny is catching up with digital platforms, posing a rising risk for social media stocks. But as Big Tobacco discovered, that's not always a bad outcome for shareholders.
00
About NasdaqGS:CORZ
Core Scientific
Provides infrastructure for high-density colocation services and digital asset mining in the United States.
High growth potential with low risk.
Similar Companies
Market Insights


Advertisement
Weekly Picks
CE


Ceazar on Sparc AI ·
When GPS fails: this small cap is fixing a $54B drone problem
Fair Value:CA$5.2540.0% undervalued
185 followersusers have followed this narrative
0 commentsusers have commented on this narrative
29 likesusers have liked this narrative
WE


WealthAP on Copart ·
Copart’s Share Price Fell. Its Moat Did Not.
Fair Value:US$4937.2% undervalued
39 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
IV


Ivoed on ASML Holding ·
ASML’s China Sell-Off Looks Overdone, Yet The Shares Are Not Cheap
Fair Value:€1.78k17.2% undervalued
27 followersusers have followed this narrative
0 commentsusers have commented on this narrative
8 likesusers have liked this narrative
FU


FundamentalContrarianInvestor on Universal Music Group ·
Universal Music Group: The Market Is Pricing the Quarter, Not the Catalogue
Fair Value:€23.2539.7% undervalued
10 followersusers have followed this narrative
0 commentsusers have commented on this narrative
3 likesusers have liked this narrative
Recently Updated Narratives
JO


John_Eric on Autodesk ·
Autodesk Fell 35%. I Asked AI to Kill the Moat. It Couldn't.
Fair Value:US$37042.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
JO

John_Eric on Meta Platforms ·
META: The Tide Just Went Out. Let's See Who's Dressed.
Fair Value:US$628.182.6% overvalued
19 followersusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
IS

isidrohg on Astera Labs ·
Astera Labs Owns The Bottleneck That Isn't Physical — And That Cuts Both Ways
Fair Value:US$628.8354.8% undervalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
AN


AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8327.9% undervalued
1411 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
AN

AnalystConsensusTarget on Alphabet ·
GOOGL: AI Platform Expansion And Cloud Demand Will Support Durable Performance Amid Competitive Pressures
Fair Value:US$427.8922.3% undervalued
1598 followersusers have followed this narrative
0 commentsusers have commented on this narrative
19 likesusers have liked this narrative
AN

AnalystConsensusTarget on Amazon.com ·
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32723.0% undervalued
1624 followersusers have followed this narrative
1 commentusers have commented on this narrative
16 likesusers have liked this narrative

