Advertisement
- United States
- /
- IT
- /
- NasdaqGS:APLD
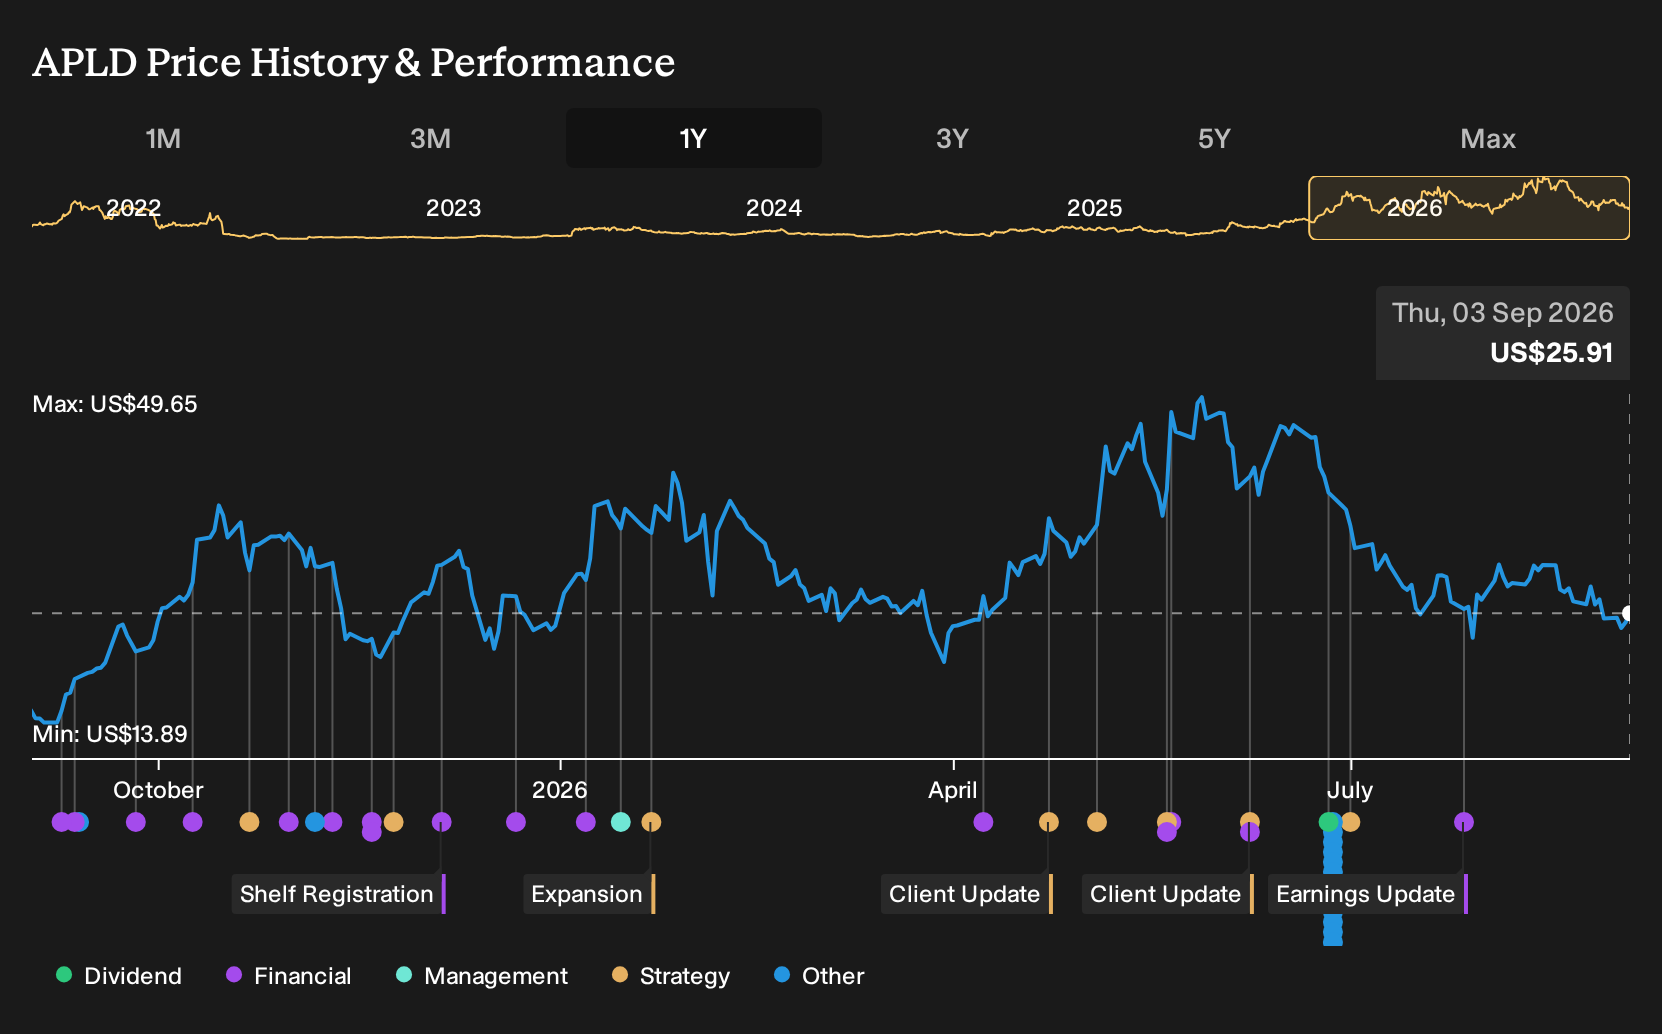
Applied Digital (APLD) Is Down 5.6% After Higher Yields Pressure Backlog Value And Financing Costs
SI

Reviewed by Sasha Jovanovic
- In recent months, Applied Digital has faced renewed pressure as rising 10-year Treasury yields increased expected financing costs and reduced the present value of its large contracted revenue backlog, even as its build program runs slightly ahead of stated capacity and long-term AI infrastructure commitments remain in place.
- This tension between a very large, multi-year revenue backlog and higher discount rates on future cash flows has sharpened investor focus on how effectively Applied Digital can execute its construction plans and convert contracted demand into realized earnings.
- Against this backdrop of higher Treasury yields pressuring financing and valuation assumptions, we'll examine how the news reshapes Applied Digital's investment narrative.
The future of work is here. Discover the 36 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
Applied Digital Investment Narrative Recap
To own Applied Digital today, you have to believe its US$36 billion, mostly hyperscaler-backed backlog will outweigh near term financing and execution pressures. The recent rise in 10-year Treasury yields directly affects both borrowing costs and how the market values that backlog, so it heightens, rather than changes, the key near term catalyst of on-time build delivery and the central risk of capital intensity and leverage.
The June 8 revolving credit facility with Goldman Sachs, providing up to US$350 million plus a US$200 million accordion, is especially relevant here. It gives Applied Digital more flexibility to fund projects like Polaris Forge and Delta Forge even as higher yields bite, but it also reinforces the importance of disciplined borrowing and timely conversion of its long-term leases into cash flow.
Yet behind the contracted revenue story, investors should be aware of how rising debt, higher rates, and construction risks could all intersect...
Read the full narrative on Applied Digital (it's free!)
Applied Digital's narrative projects $2.4 billion revenue and $117.0 million earnings by 2029.
Uncover how Applied Digital's forecasts yield a $73.36 fair value, a 183% upside to its current price.
Exploring Other Perspectives
Some of the lowest analysts were already assuming about 59.6 percent annual revenue growth and no profits by 2029, so after a sharp yield-driven selloff, you can see how views on heavy debt and long lease reliance might diverge sharply and why it is worth comparing several different scenarios before deciding what you think comes next.
Explore 9 other fair value estimates on Applied Digital - why the stock might be worth over 4x more than the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Applied Digital research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- Our free Applied Digital research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate Applied Digital's overall financial health at a glance.
Seeking Other Investments?
The market won't wait. These fast-moving stocks are hot now. Grab the list before they run:
- Uncover the next big thing with 22 elite penny stocks that balance risk and reward.
- AI is about to change healthcare. These 37 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
- Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 30 best rare earth metal stocks of the very few that mine this essential strategic resource.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: Manage All Your Stock Portfolios in One Place
We've created the ultimate portfolio companion for stock investors, and it's free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
M

The Foxhole
You can copy Bill Ackman and buy Netflix. Knowing why you did is the hard part.

710
f
frank_ub3n0
Netflix case is interesting. The scariest competitor is the one that does not need to make money. Amazon can run video at a loss forever because it is really a Prime retention tool with a content budget attached. On the other hand there is Youtube.
a
arjun_dyig0
Pershing Square hasn't beaten the S&P over the last five years, though the long-run record is genuinely good. I like Ackman as a person. I enjoy listening to Ackman and that's about where it ends for me.
 Mitchell Lawler
Market Insights
What 13F filings won't tell you about a billionaire's stock picks

Fresh 13F filings are where some investors go to find their next stock pick. The problem is it's missing some of the most important details for making a good investment.
10
About NasdaqGS:APLD
Applied Digital
Designs, develops, and operates digital infrastructure solutions to high-performance computing (HPC) and artificial intelligence industries in North America.
High growth potential with low risk.
Similar Companies
Market Insights


Advertisement
Weekly Picks
LO


Lou_Basenese on Oncolytics Biotech ·
The Team Behind a $2 Billion Johnson & Johnson (JNJ) Deal Just Took Over This $105 Million Cancer Biotech
Fair Value:US$3.575.5% undervalued
61 followersusers have followed this narrative
1 commentusers have commented on this narrative
15 likesusers have liked this narrative
AN


andrei9868 on ServiceNow ·
The Platform Turning Enterprise Chaos into Autonomous Workflows
Fair Value:US$17014.4% undervalued
43 followersusers have followed this narrative
2 commentsusers have commented on this narrative
10 likesusers have liked this narrative
JO


John_Eric on Vistra ·
Vistra Fell 38%. Adjusted EBITDA Rose 31%. Here's the $472 Million Reason They Disagree.
Fair Value:US$291.8750.6% undervalued
43 followersusers have followed this narrative
2 commentsusers have commented on this narrative
17 likesusers have liked this narrative
HA


HarishPK on EverQuote ·
EverQuote and an Asymmetric Investment Opportunity
Fair Value:US$36.0929.9% undervalued
11 followersusers have followed this narrative
4 commentsusers have commented on this narrative
6 likesusers have liked this narrative
Recently Updated Narratives
LU


LunaRodas on KNOT Offshore Partners ·
KNOP | KNOT Offshore Partners LP: What They Said vs. What They Did
Fair Value:US$10.774.3% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
AS


AstrisCorporateAdvisory on Ryobi ·
Entering a year of earnings consolidation
Fair Value:JP¥2.37k15.9% overvalued
1 followerusers have followed this narrative
0 commentsusers have commented on this narrative
0 likesusers have liked this narrative
BL


Blagget on Terra Balcanica Resources ·
The C$4M Explorer Positioned to Become Europe's First Antimony Mine
Fair Value:CA$0.490.0% undervalued
6 followersusers have followed this narrative
1 commentusers have commented on this narrative
0 likesusers have liked this narrative
Popular Narratives
OS


oscargarcia on NVIDIA ·
The company that went from selling GPUs to gamers to becoming the AI arms dealer of the 21st century.
Fair Value:US$28018.4% undervalued
374 followersusers have followed this narrative
9 commentsusers have commented on this narrative
17 likesusers have liked this narrative
JO

John_Eric on MercadoLibre ·
MercadoLibre and the Spreadsheet Trick That Decides Everything
Fair Value:US$3.68k45.8% undervalued
129 followersusers have followed this narrative
3 commentsusers have commented on this narrative
18 likesusers have liked this narrative
AN

AnalystConsensusTarget on NVIDIA ·
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8324.6% undervalued
1364 followersusers have followed this narrative
8 commentsusers have commented on this narrative
35 likesusers have liked this narrative
